One of my favorite parts about The White Coat Investor is the opportunity to have a bit of a “personal ministry” on the side, via the comments section of the blog, our online communities, and especially my email inbox. It is particularly gratifying when the loop gets closed years later. I had that experience again recently, and I thought you might enjoy getting an inside look at what’s really happening here at WCI.
May 5, 2015 — An Emailed Question
Date: Tue, May 05, 2015 5:01 pm
To: [email protected]
Subject: PSLF vs DRB
Hi WCI,
I’m a graduating fourth-year medical student who stumbled upon your blog a couple of weeks ago and have been reading voraciously ever since. My copy of Personal Finance for Dummies is in the mail as I type. I have a question/conundrum that I realize might sound like asking you to predict the legislative future but would appreciate any input or advice you have regardless. I have about $258,000 (including accrued interest) in medical student loans, am 27 years old, matched at a 501(c)3 for neurology residency, single, no kids, but with a serious boyfriend who is a year behind me in medical school.
For me, the dilemma is PSLF vs. refinancing through DRB [now KeyBank, one of WCI’s advertising partners]. Arguments for PSLF are 1) my debt burden is pretty terrible, 2) I will be halfway through the 10 years by the time I’m done with fellowship, 3) it’s fairly likely I would continue at an academic institution as a young attending, 4) I’ve been told by my financial aid counselor that the proposed changes are unlikely to take effect before October 2016 since they are not even resolutions yet [and] that I would likely be grandfathered in to the existing program because I’ve signed MPNs each year. Even if the forgiveness [is] capped at $57,000, I would benefit from having even that much of my debt forgiven. [For those unaware, the Obama administration in 2015 proposed capping PSLF at $57,000.]
Arguments against PSLF: the program could become significantly altered or cease to exist, and if I’ve put all my eggs in the forgiveness basket, I will have made minimal payments throughout residency and have interest growing at 6.5% as opposed to a lower, refinanced rate. If I decide against PSLF, I’d probably refinance with DRB. It seems like the best option, and one of their reps is going to go through different repayment scenarios with me within the week.
Any thoughts about how to go about making the decision? Any other information I should try to get? I will be looking at a starting attending salary of about $217,000. If my boyfriend and I get married, his will be substantially higher (he wants to do IR), and he also is graduating with significantly less debt ($90,000). Thank you in advance for any advice!
My Response
Date: Tue, May 5, 2015 at 8:48 PM
Subject: RE: The White Coat Investor Contact: PSLF vs DRB
The email before yours has $510,000 in student loans, so don’t feel too badly. The best financial advice I have is that you should marry that radiologist with only $90,000 in debt. 🙂
That said, you understand the dilemma very well. I have no idea if PSLF will go away, and if you go for it and it does and you’re not grandfathered, then you would have been better off refinancing. But if I were you, I’d probably go for PSLF and keep a small but growing fund on the side you can use to pay off the loans if the program changes.
Jim
James M. Dahle, MD, FACEP
Editor
The White Coat Investor
So far, so good. I gave this advice to many people for many years (and still do) to keep a PSLF Side Fund. That protects against legislative risk; executive risk; judicial risk; and most importantly, career risk (in case you don’t want to work full-time for a 501(c)3 anymore.) Unbeknownst to me, after we started StudentLoanAdvice.com in 2021, this WCIer met with our lead consultant there, Andrew Paulson. Now, imagine my joy at receiving the following email in 2026.
January 22, 2026 — The Rest of the Story
Date: Thu, Jan 22, 2026 at 7:04 AM
Subject: Good news, and a blast from the past
To: Andrew Paulson, Jim Dahle
Got some good news this month—my loans (total $336,000, given accrued interest on the principal) were forgiven via PSLF!!! I include my original email to Jim more than 10 years ago as I was finishing medical school—he wasn’t quite the household name he is today. Zeroed out balance as of yesterday, got the golden letter a couple weeks back, and now awaiting a month’s payment refund from MOHELA.
I DID marry the radiologist, and we have two amazing boys whose mother is now, happily, debt-free 🙂 Thank you, too, for your consult/advice a few years back!
How The White Coat Investor Helps Doctors
Pretty fun, right? Now you know what keeps Katie and me doing this years out from our own financial independence. Several things about WCI make this sort of thing possible, and we’re really proud of them.
#1 Just in Time Education
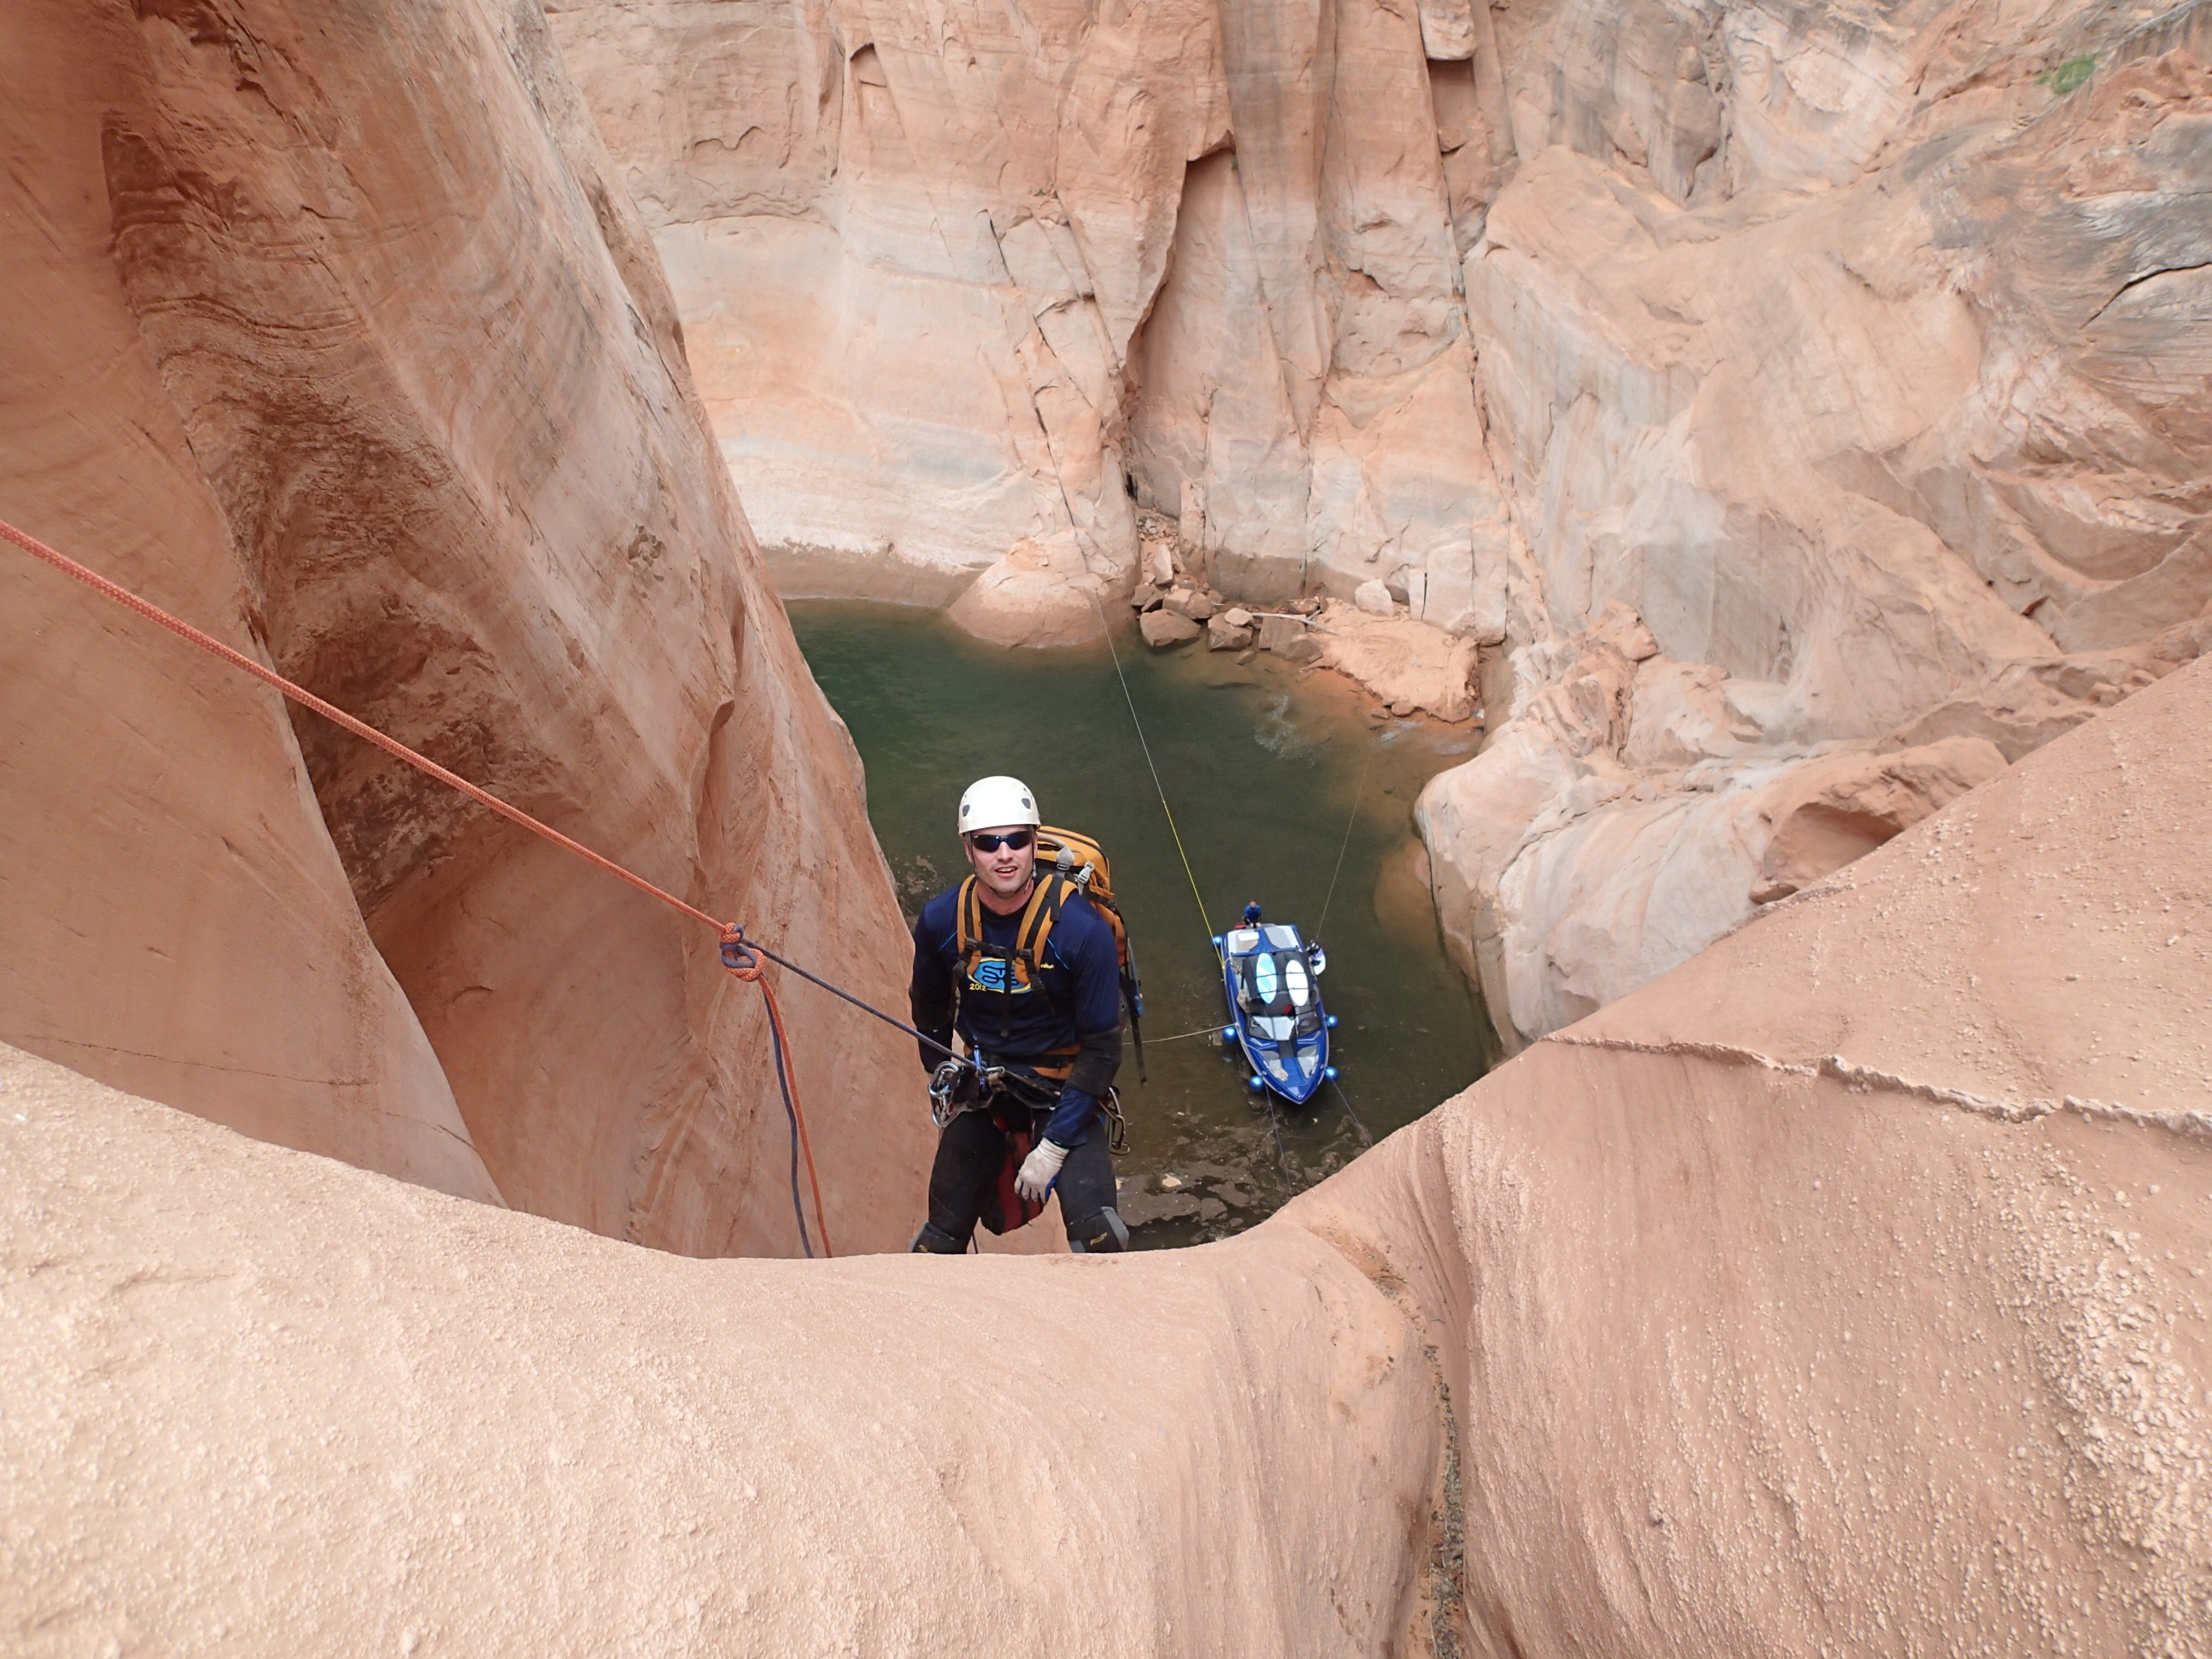
We know doctors are busy. When I wrote that email in 2015, I was working full-time as an emergency physician AND putting in the equivalent of full-time work at WCI. We had one employee, and she wasn’t working full-time. Katie was nearly eight months pregnant with our youngest child, now 10 years old. We’d just bought a boat (using WCI profits, which were definitely less than I was making clinically at that point), and the next week, I would be wedging it into the bottom of a slot canyon for the first time on its first day on the water. I’ve since made 25+ canyoneering trips in that boat.
But when doctors are ready to become financially literate and disciplined, they need access to this high-yield information NOW. Thus, WCI is now a website, blog, books, online courses, online communities, podcasts, emailed newsletters, and social media feeds. When the student is ready, the teacher shall appear. WCI had been around for four years prior to this WCIer finding it. And it’s been around for 11 years since, helping hundreds of thousands more.
More information here:#2 Free
We’ve debated over the years about putting WCI behind a paywall. Essentially, we’d be making it a subscription service. That would allow us to get rid of all the ads (who likes ads?) while still making a profit. But we think it would dramatically reduce how many people it helps. We know most of you have never paid us a dime. Maybe you used an advertiser or two of ours over the years. Or maybe you bought a book, and we made $8. That’s OK. We’ve figured out a way to make this both profitable for us (which is important so we can hire staff, provide scholarships, give out an educator award, pass out WCI books to MS-1s and PGY-1s, and buy a boat every now and then) and almost entirely free to you.
Ninety-eight percent of the content we produce is literally given away. Would this WCIer have read up on PSLF and emailed this question to me if she had had to pay thousands of dollars upfront to us? Almost surely not. It would have been worth paying that, of course, but she didn’t know that yet. I suck at selling anyway.
#3 Persistent
You know what the difference is between WCI and almost all of the other 100+ physician financial blogs that have existed? We didn’t quit. We’re still here. Ten years later. Fifteen years later. Hopefully, 100 years later, still helping doctors. We’re still in the game, and each year, we help more and more. That’s why we could reassure this WCIer to keep going for PSLF in 2015, in 2021, and probably numerous other times over the last decade. And now, her net worth increased by $336,000 after-tax in one day. Pretty awesome. Forgive me for taking a victory lap.
More information here:#4 Connecting WCIers with the Good Guys
One of the most important things we do here at WCI is connect our audience with professionals who can give them good advice and good service at a fair price. We think this is so important that we measure these connections every month. There are literally thousands of them. We think this is so important that here I am the day after surgery in our recording studio typing on my computer with a splint and an ice bag on my arm.
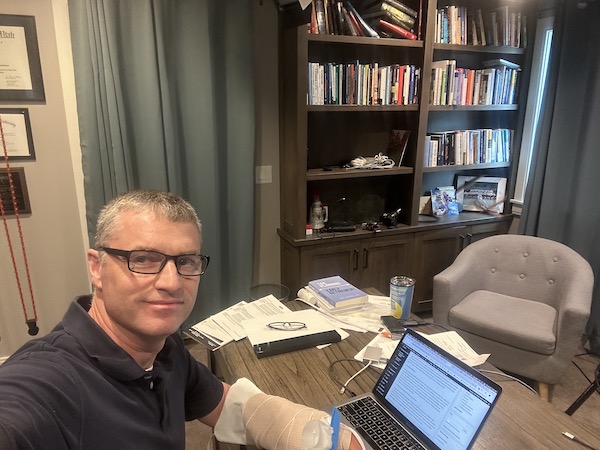
Unlike 10 years ago, I have a few gray hairs and have to wear reading glasses. Nineteen of us are working here now, not two, but we all still feel at least as passionately about the WCI Mission as Cindy, Katie, and I did a decade ago. In this particular case, this WCIer was connected with StudentLoanAdvice.com, a company WE STARTED to meet a need YOU had. But by spending a few hundred bucks with a great company, the emailer maximized how much she received via PSLF. Now StudentLoanAdvice.com has been folded into White Coat Planning, another company WE STARTED to meet a need YOU had.
Yeah, I’m having a pretty good time today, as you can probably tell. My surgery went well the day before I wrote this, and yes, I am off the narcotics already (Katie hid my computer until I was off them). We hope WCI has made as big a difference in your life as it has in ours and in the life of this WCIer. If not, give it a little time. We wish you success in your life, your career, and your finances. We truly believe that financially stable doctors are better partners, parents, and physicians.
What do you think? How has WCI helped you over the years? What year did you discover this community?
Did you find this article helpful? Share it!