Life insurance might actually be the easiest insurance to shop for, and The White Coat Investor is making it as easy as we possibly can with our new term life insurance quoting tool. You can find it here:
You know what I find more depressing than just about anything? Cruising along on social media and finding out some young parent with small children just died and their friends are trying to raise some cash for the survivors via GoFundMe. I’ve got some news for you. GoFundMe is NOT an insurance company. The median GoFundMe raise is $2,000. That doesn’t go very far for a family that just lost a breadwinner.
Is that really what you want your family to have if something terrible happens to you? Probably not. So, go get some insurance.
Let’s go through that link above and try out our new tool. It’ll look like this:
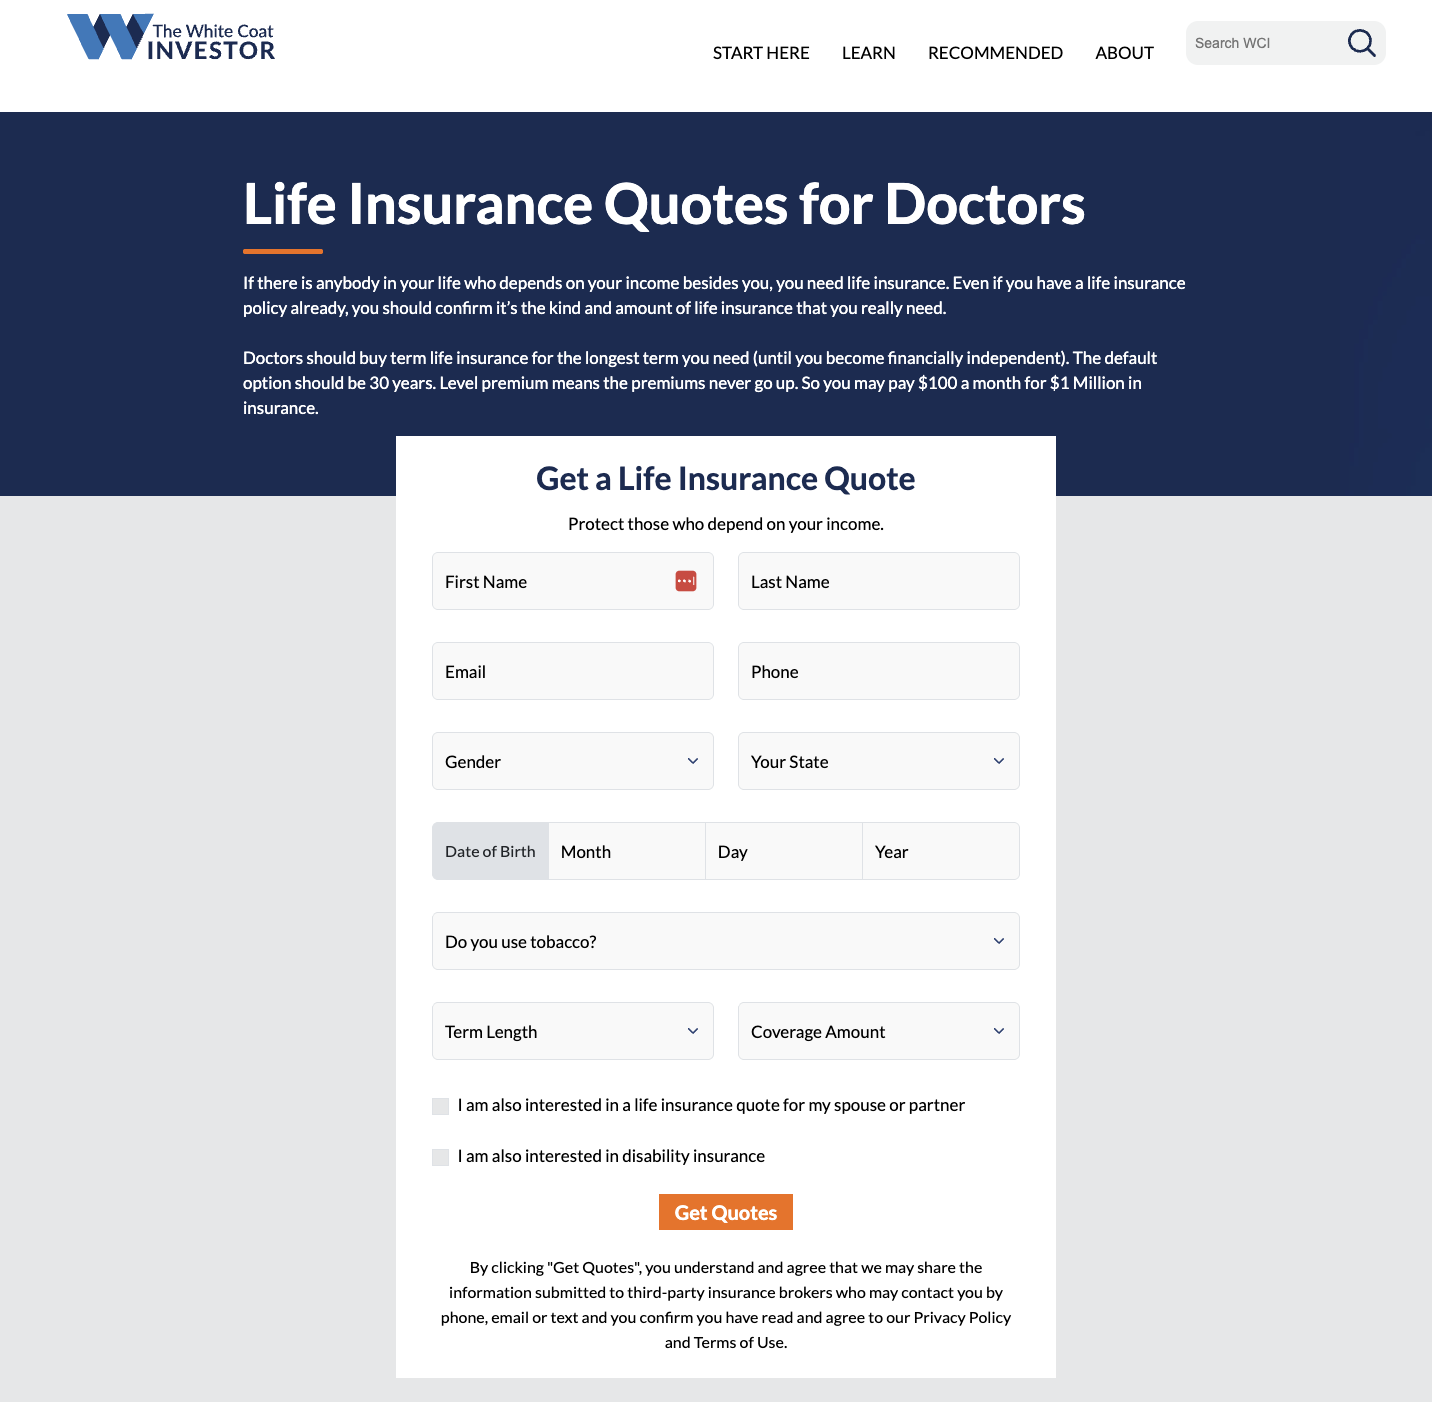
Fill it out, and hit “Get Quotes.”
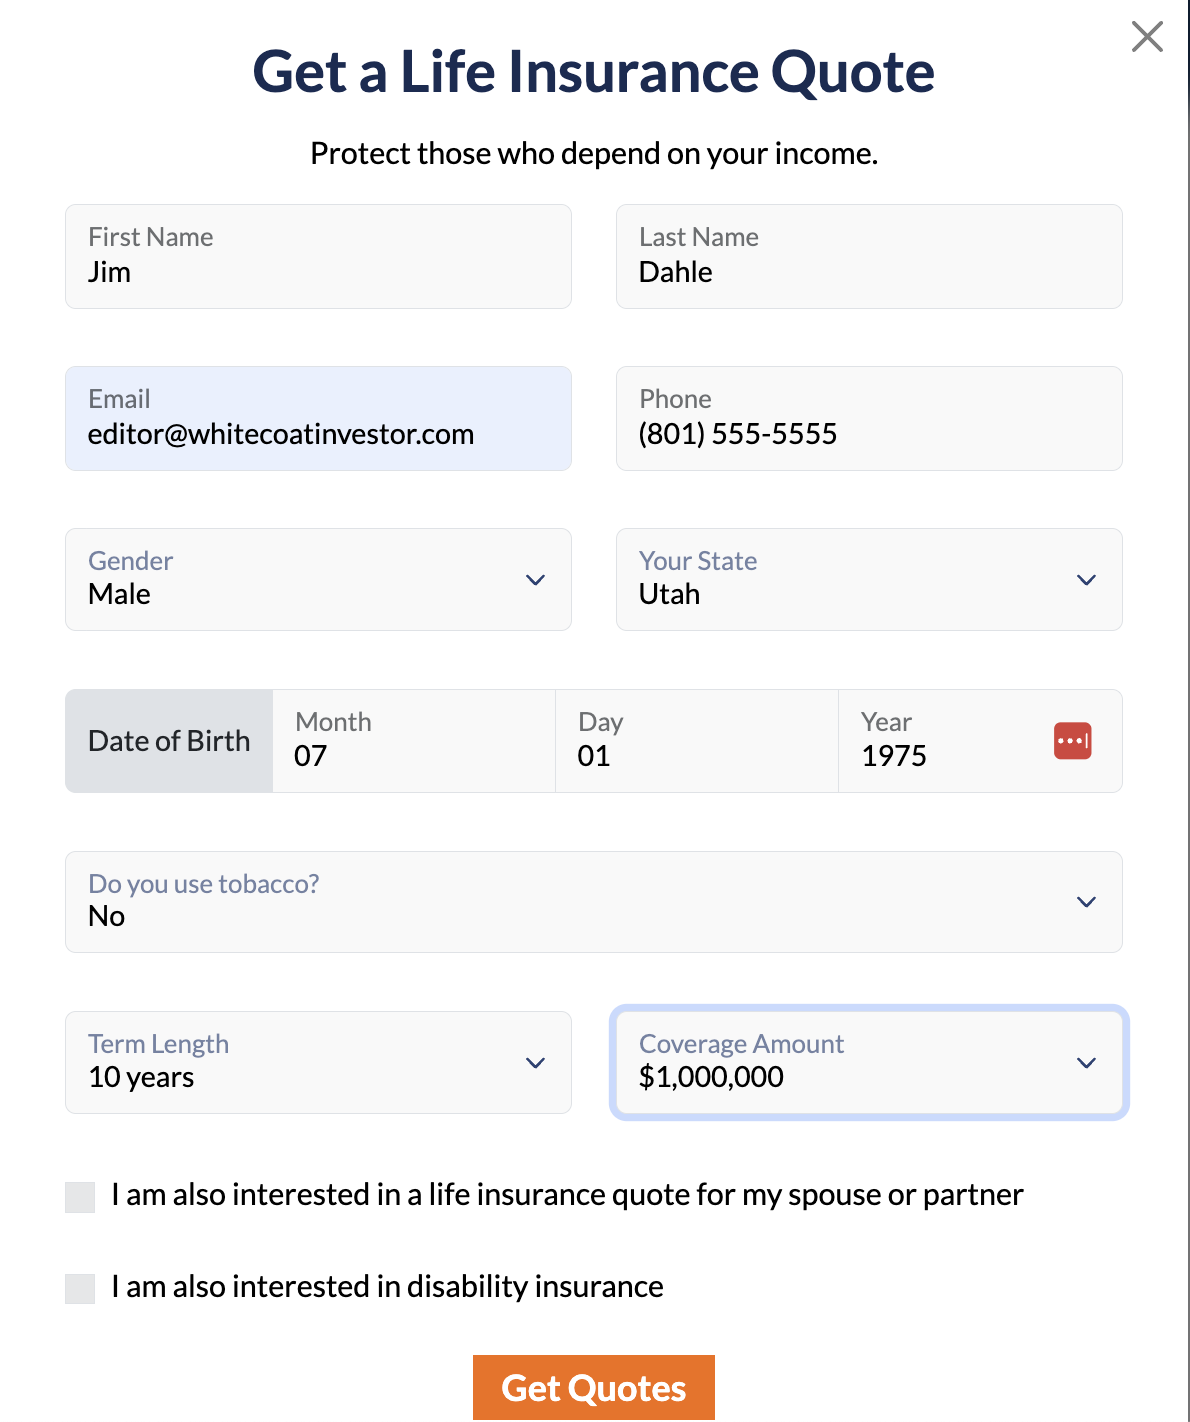
When I fill it out, it shows me this.
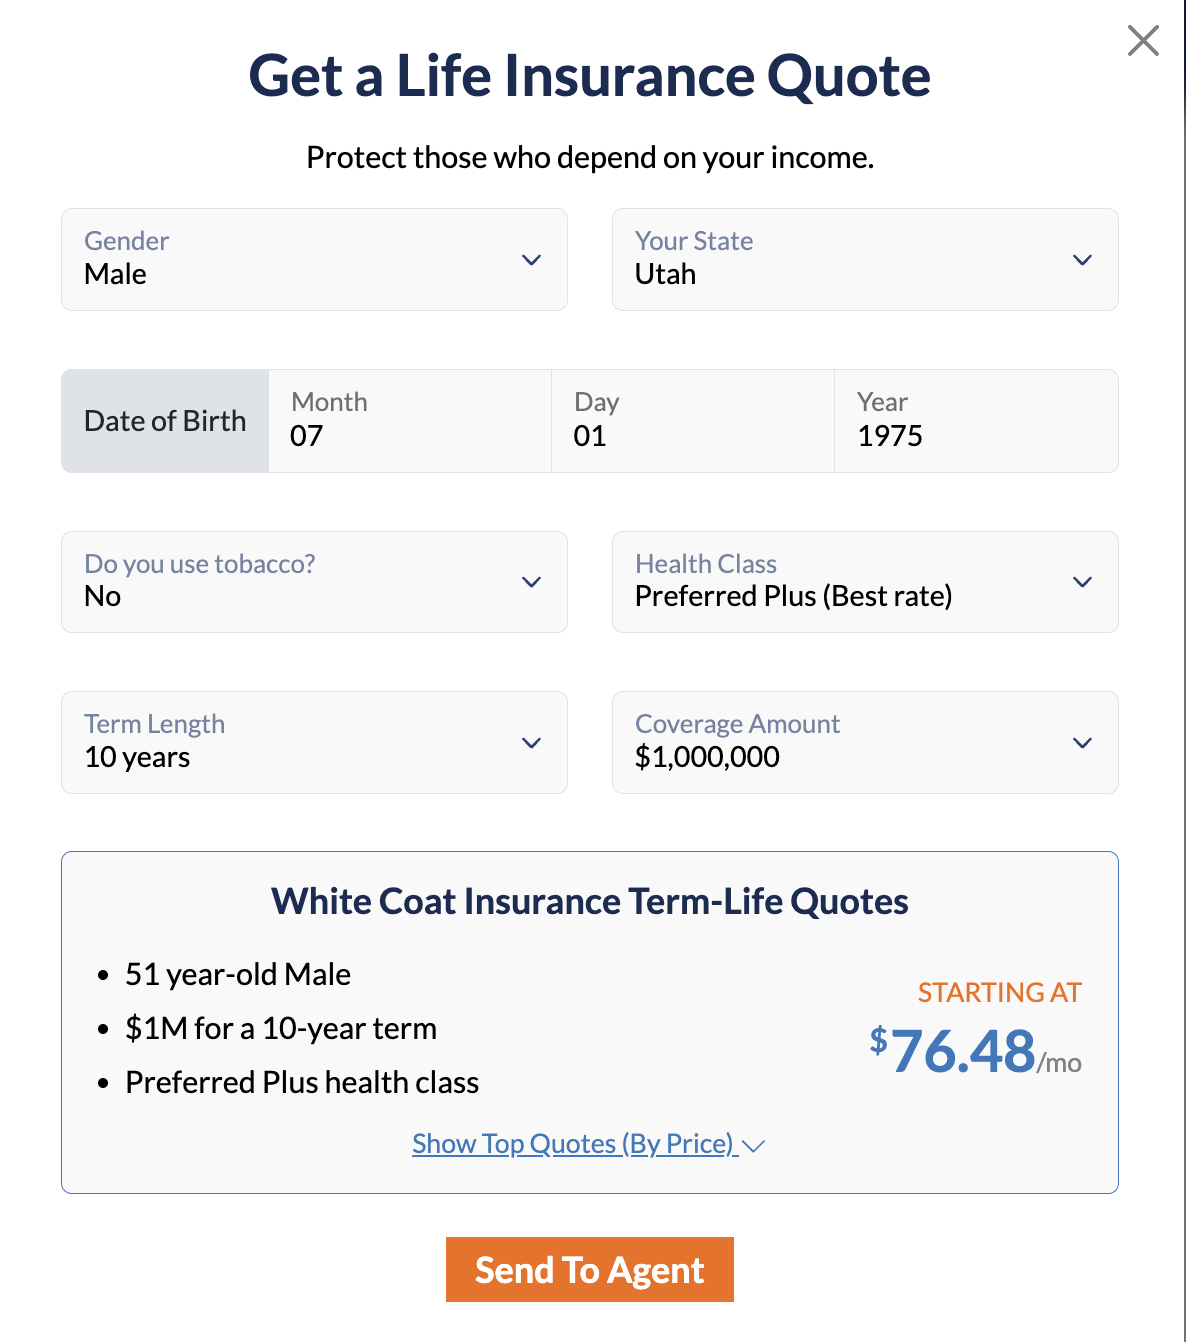
Which says I could potentially get $1 million in coverage, even at age 51, for less than $1,000 a year ($76.48*12 = $917.76). I say “potentially” because other than tobacco, it hasn’t asked me a thing about my medical problems or hobbies. There is a drop-down menu where I can see a more “worst-case” scenario, one where it says “Health Class.” The options are:
- Preferred Plus (Best Rate)
- Preferred (Excellent)
- Standard Plus (Above Average)
- Standard (Average)
Now, you can adjust anything you want, and the quote will adjust automatically. So easy.
Let’s look up the worst case possible, which is that my health is average. If I do that, I see my quotes start at $161.90 a month, or $1,942.80 per year for $1 million in coverage for 10 years. Now, let’s see all the top quotes. Moving me back to “Preferred Plus,” we see this.
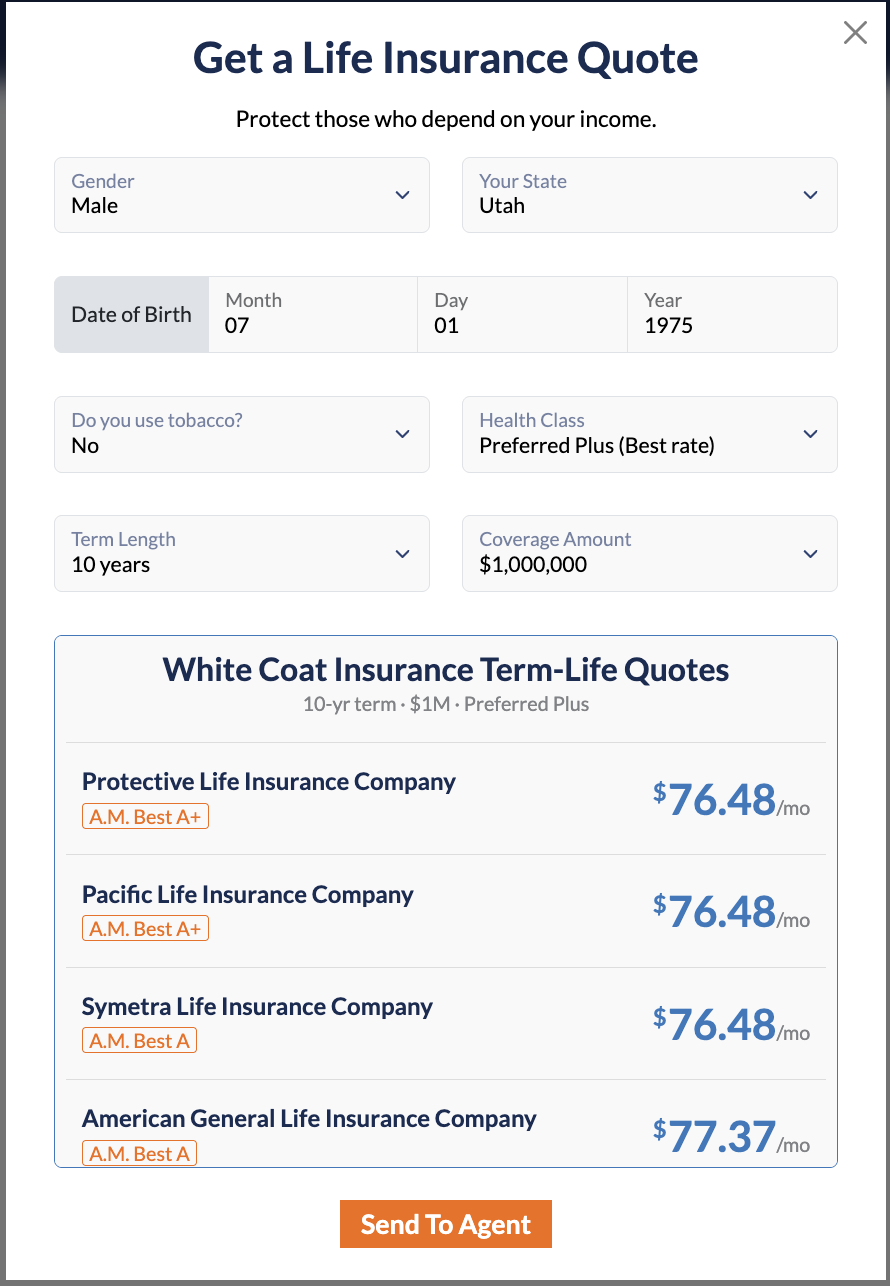
We see that three companies are willing to insure me for $76.48 per month, plus another 15 are willing to insure me for $77.37 to $104.28. Now, I’m going to hit “Send To Agent” and see what happens. I see this notice and some more information about buying life insurance.
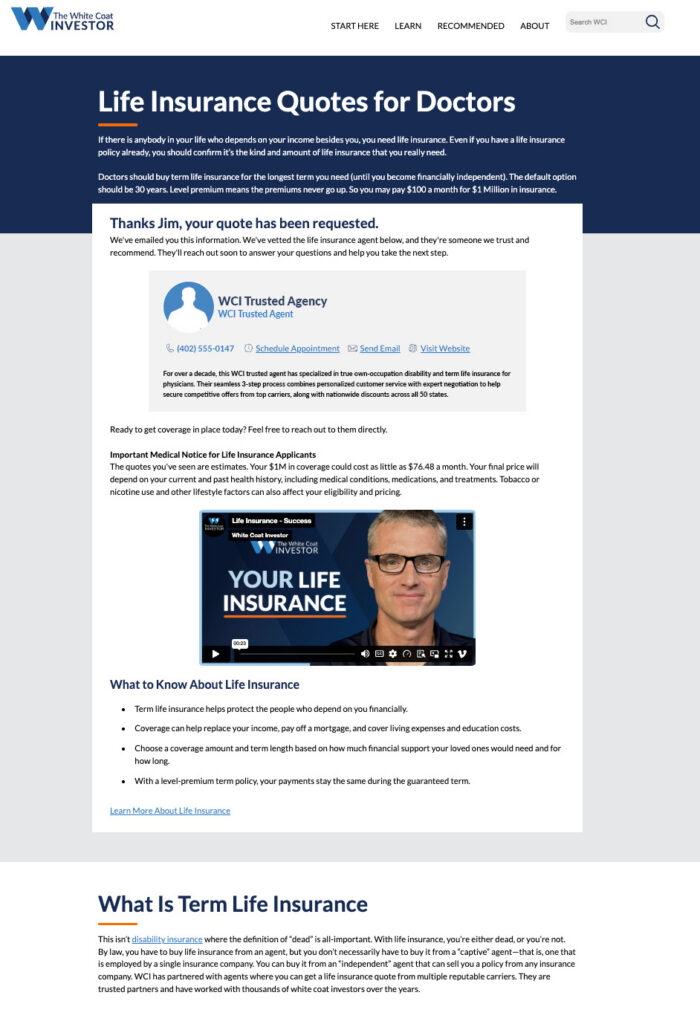
At this point, your information (my information in this case) has been sent to WCI-vetted insurance agents. I filled this out on a weekend (when I wrote this blog post), but I bet an email or a call will come from them on Monday. Super slick. Super easy. Only one insurance agent contacting you. And you work together with that agent to get your policy in place. Expect a paramedic exam (a few questions, vital signs, blood and urine) and that the insurance company underwriters will check their databases. Then, if you pass underwriting, you’ll be offered a policy. Less than a month after you fill out this form, your loved ones are protected. I seriously don’t know how we can make this easier for you.
I’ve also got an email in my inbox. It looks like this:
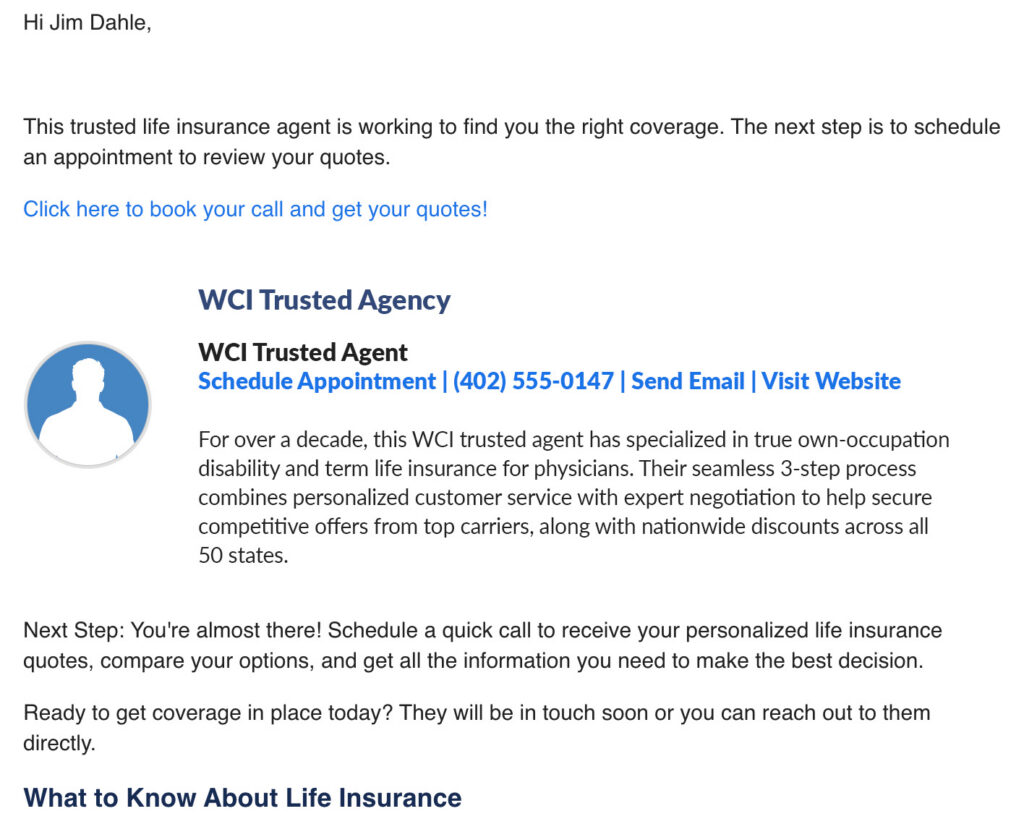
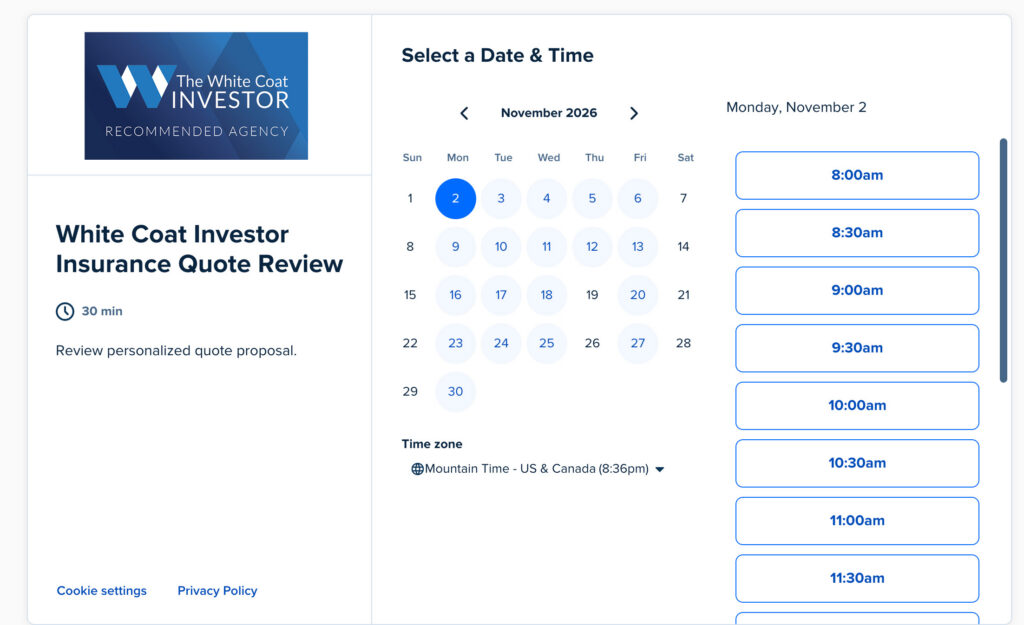
There may be an option to schedule an appointment either this week or a few weeks from now.
How Much Does Life Insurance Cost for Physicians?
I know most of you shopping for life insurance aren’t 51 like me. Hopefully. I mean, Katie and I had life insurance for decades, but we don’t have any now because we’re financially independent. Hopefully most of you are buying this at 25 or 30 or 35, when someone besides you begins relying on your income. Of course, you probably also need insurance for longer than 10 years, more like 20-30.
If we use this database to get that information, we can make a chart. Let’s price out a $1 million policy, paid monthly, for 20-30 years for 25-, 30-, and 35-year-old super healthy women and men. Note that if you actually pay annually, it’s slightly cheaper than this.
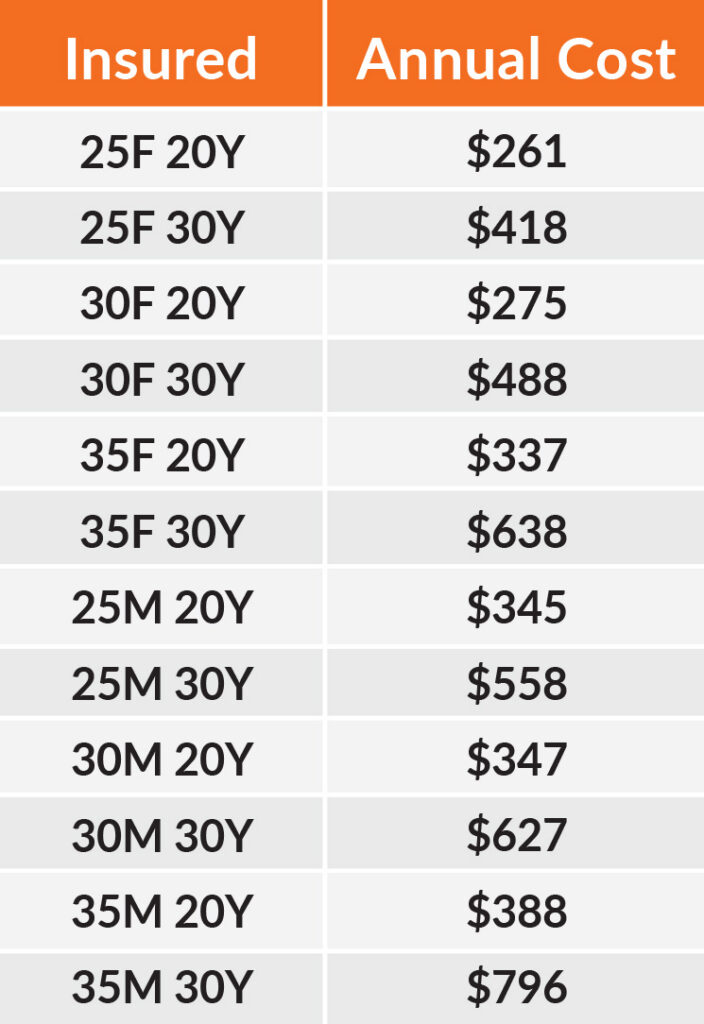
We can learn a few things from this chart. The first is that term life insurance is cheap compared to most other types of insurance we buy. Many of you are paying five figures a year for malpractice insurance. Disability insurance, even when bought when young and healthy, typically costs 2%-6% of the amount covered, so it’s $300-$900 per MONTH for a policy with a $15,000 monthly benefit. But with life insurance, your heir can get the equivalent of 5 1/2 years of those disability benefits all up front for less than 10% of the cost. Super cheap; no excuse not to buy it.
The second thing to learn is that this stuff is cheaper if you buy it younger. This shouldn’t be a surprise. Young people are less likely to die. More importantly, younger people are less likely to have any medical problems that bump them out of Preferred Plus.
The third thing to learn is that women can buy life insurance cheaper than men can. Again, they’re less likely to die, though they sometimes have to pay more for disability insurance than men do.
Finally, realize how much cheaper it is to buy a 20-year policy than a 30-year policy. It’s like half the price. So, figure out when you can be FI and dump your term life insurance, and then only buy life insurance until that date. Maybe give yourself a few extra years or ladder multiple policies, but hitting FI at mid-career has many benefits, not the least of which is the ability to cancel your term life and disability insurance policies.
More information here:- No Coffin, No Problem: A True Life Insurance Payout Story Where Death Wasn’t Required
- Preparing for Tragedy: Ensuring Your Partner Can Manage Without You
How Much Insurance to Buy?
I can’t imagine someone who needs life insurance who doesn’t need at least a million dollars of it. Most doctors with a need buy $1 million-$5 million. Basically, you just add up everything you want money to do if you’re not there, subtract out what you have already, and “fill the gap” with term life insurance. If you need:
- $200,000 x 3 for your kids’ college educations
- $600,000 to pay off the mortgage
- $4 million for your stay-at-home spouse to live the rest of their life
Subtract out the $50,000 you already have for college and the $750,000 you have for retirement. Total: $4 million. Maybe it’ll cost $1,300 per year ($108 per month) for a healthy 35-year-old female. No big deal. You can totally afford that.
What Health Class Would I Be In?
It can be a bit of a mystery sorting out what health class you will be in prior to underwriting. And truthfully, it doesn’t matter too much since you’re likely to get the same health class from every insurance company. But let’s give a few examples to give you an idea of how the underwriters might view you.
Preferred Plus
This is someone who has normal blood pressure, normal Body Mass Index (BMI), normal cholesterol, a clean driving record, no family history of early heart disease or cancer; takes no medications; and has no dangerous hobbies like climbing, skydiving, flying, or scuba diving.
Preferred
This is someone who barely missed out on being Preferred Plus. Slightly high blood pressure. Diet-controlled hypercholesterolemia. BMI of 30. Well-controlled sleep apnea compliant with prescribed treatment. That sort of thing.
Standard Plus
This is someone with a BMI of 35 or who has a single well-controlled medical problem on medication, like hypertension, hypercholesterolemia, or sleep apnea on CPAP.
Standard
Considered to be the average person, this is someone with a BMI of 40 with a family history of coronary disease or well-controlled diabetes. It might also be a PADI-certified scuba diver who does fewer than 50 dives a year.
Substandard (Table Ratings)
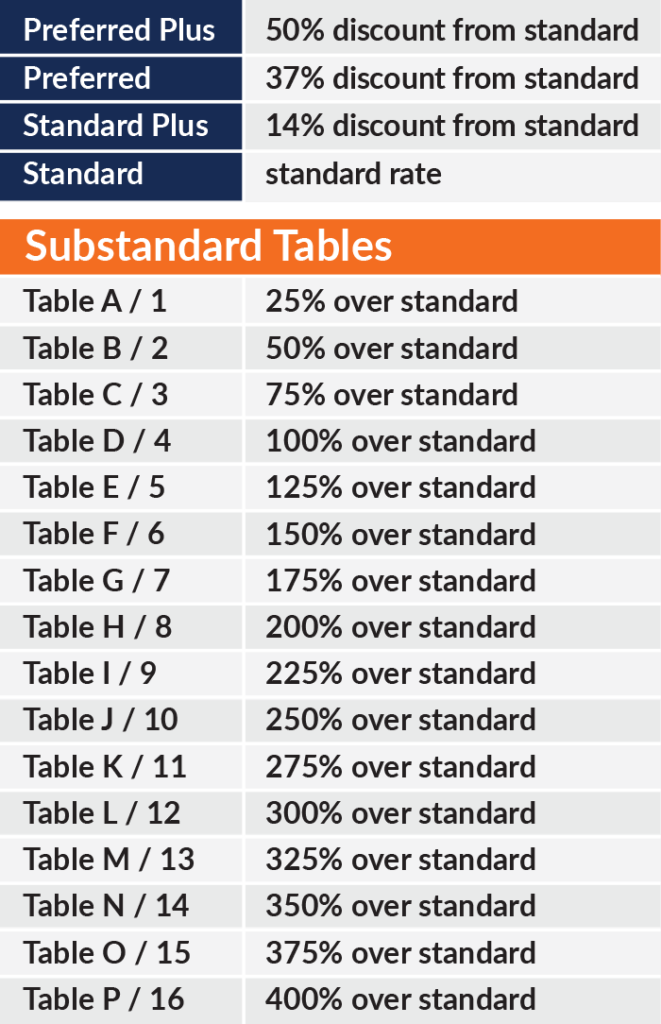
Tables are listed A-J or 1-16. Being on Table A might add 25% to standard pricing. Tables B-D might add 25%-100%. E-J might add 125%+. Here’s an example of what the “table” might look like:
Declined
Who gets declined for life insurance? Active cancer would do it. So would severe heart disease. A stroke or TIA in the last 12 months would also, as would residual symptoms such as paralysis. Poorly controlled diabetes, COPD, kidney failure, liver failure, ALS, Alzheimer’s, Parkinson’s, Huntington’s, severe MS, transplants, alcoholism, psychosis, recent psych hospitalizations, or poorly controlled bipolar or major depression with prior suicide attempts would all likely lead to a decline. Dangerous hobbies, occupations, and criminal behavior can also lead to a decline, but it’s all dependent on frequency, safety gear, and skill level.
Your options for those are using specialized carriers, getting exclusions for those activities, and paying “flat extra premiums.” Your agent can help you navigate these situations. Like with disability insurance, be completely honest with the agent and recognize they’re on your side. It’s you and your agent against the underwriter and insurance company. It’s not you against your agent, underwriter, and insurance company. They can shop you around to an insurance company that is likely to be more lenient for your condition or activity, and they can find out if you’re likely to be approved before you get a decline you have to report on future applications.
More information here:The Bottom Line
Get your term life insurance in place early. It’s cheaper when you’re younger and healthier, but most importantly, occasionally people die young. GoFundMe is my least favorite insurance company. Please don’t rely on it to take care of your loved ones.
Do you have enough life insurance? If you’ve dropped it, at what point did you feel comfortable self-insuring?
The White Coat Investor may receive compensation from White Coat Insurance Services, LLC; licensed in all states including MA and DC; CA license #6009217; NY license #1758759 (exp. 6/2027); Registered address: 10610 S. Jordan Gateway, #200 South Jordan, UT 84095. This does not affect the cost or coverage of insurance.
Did you find this article helpful? Share it!