
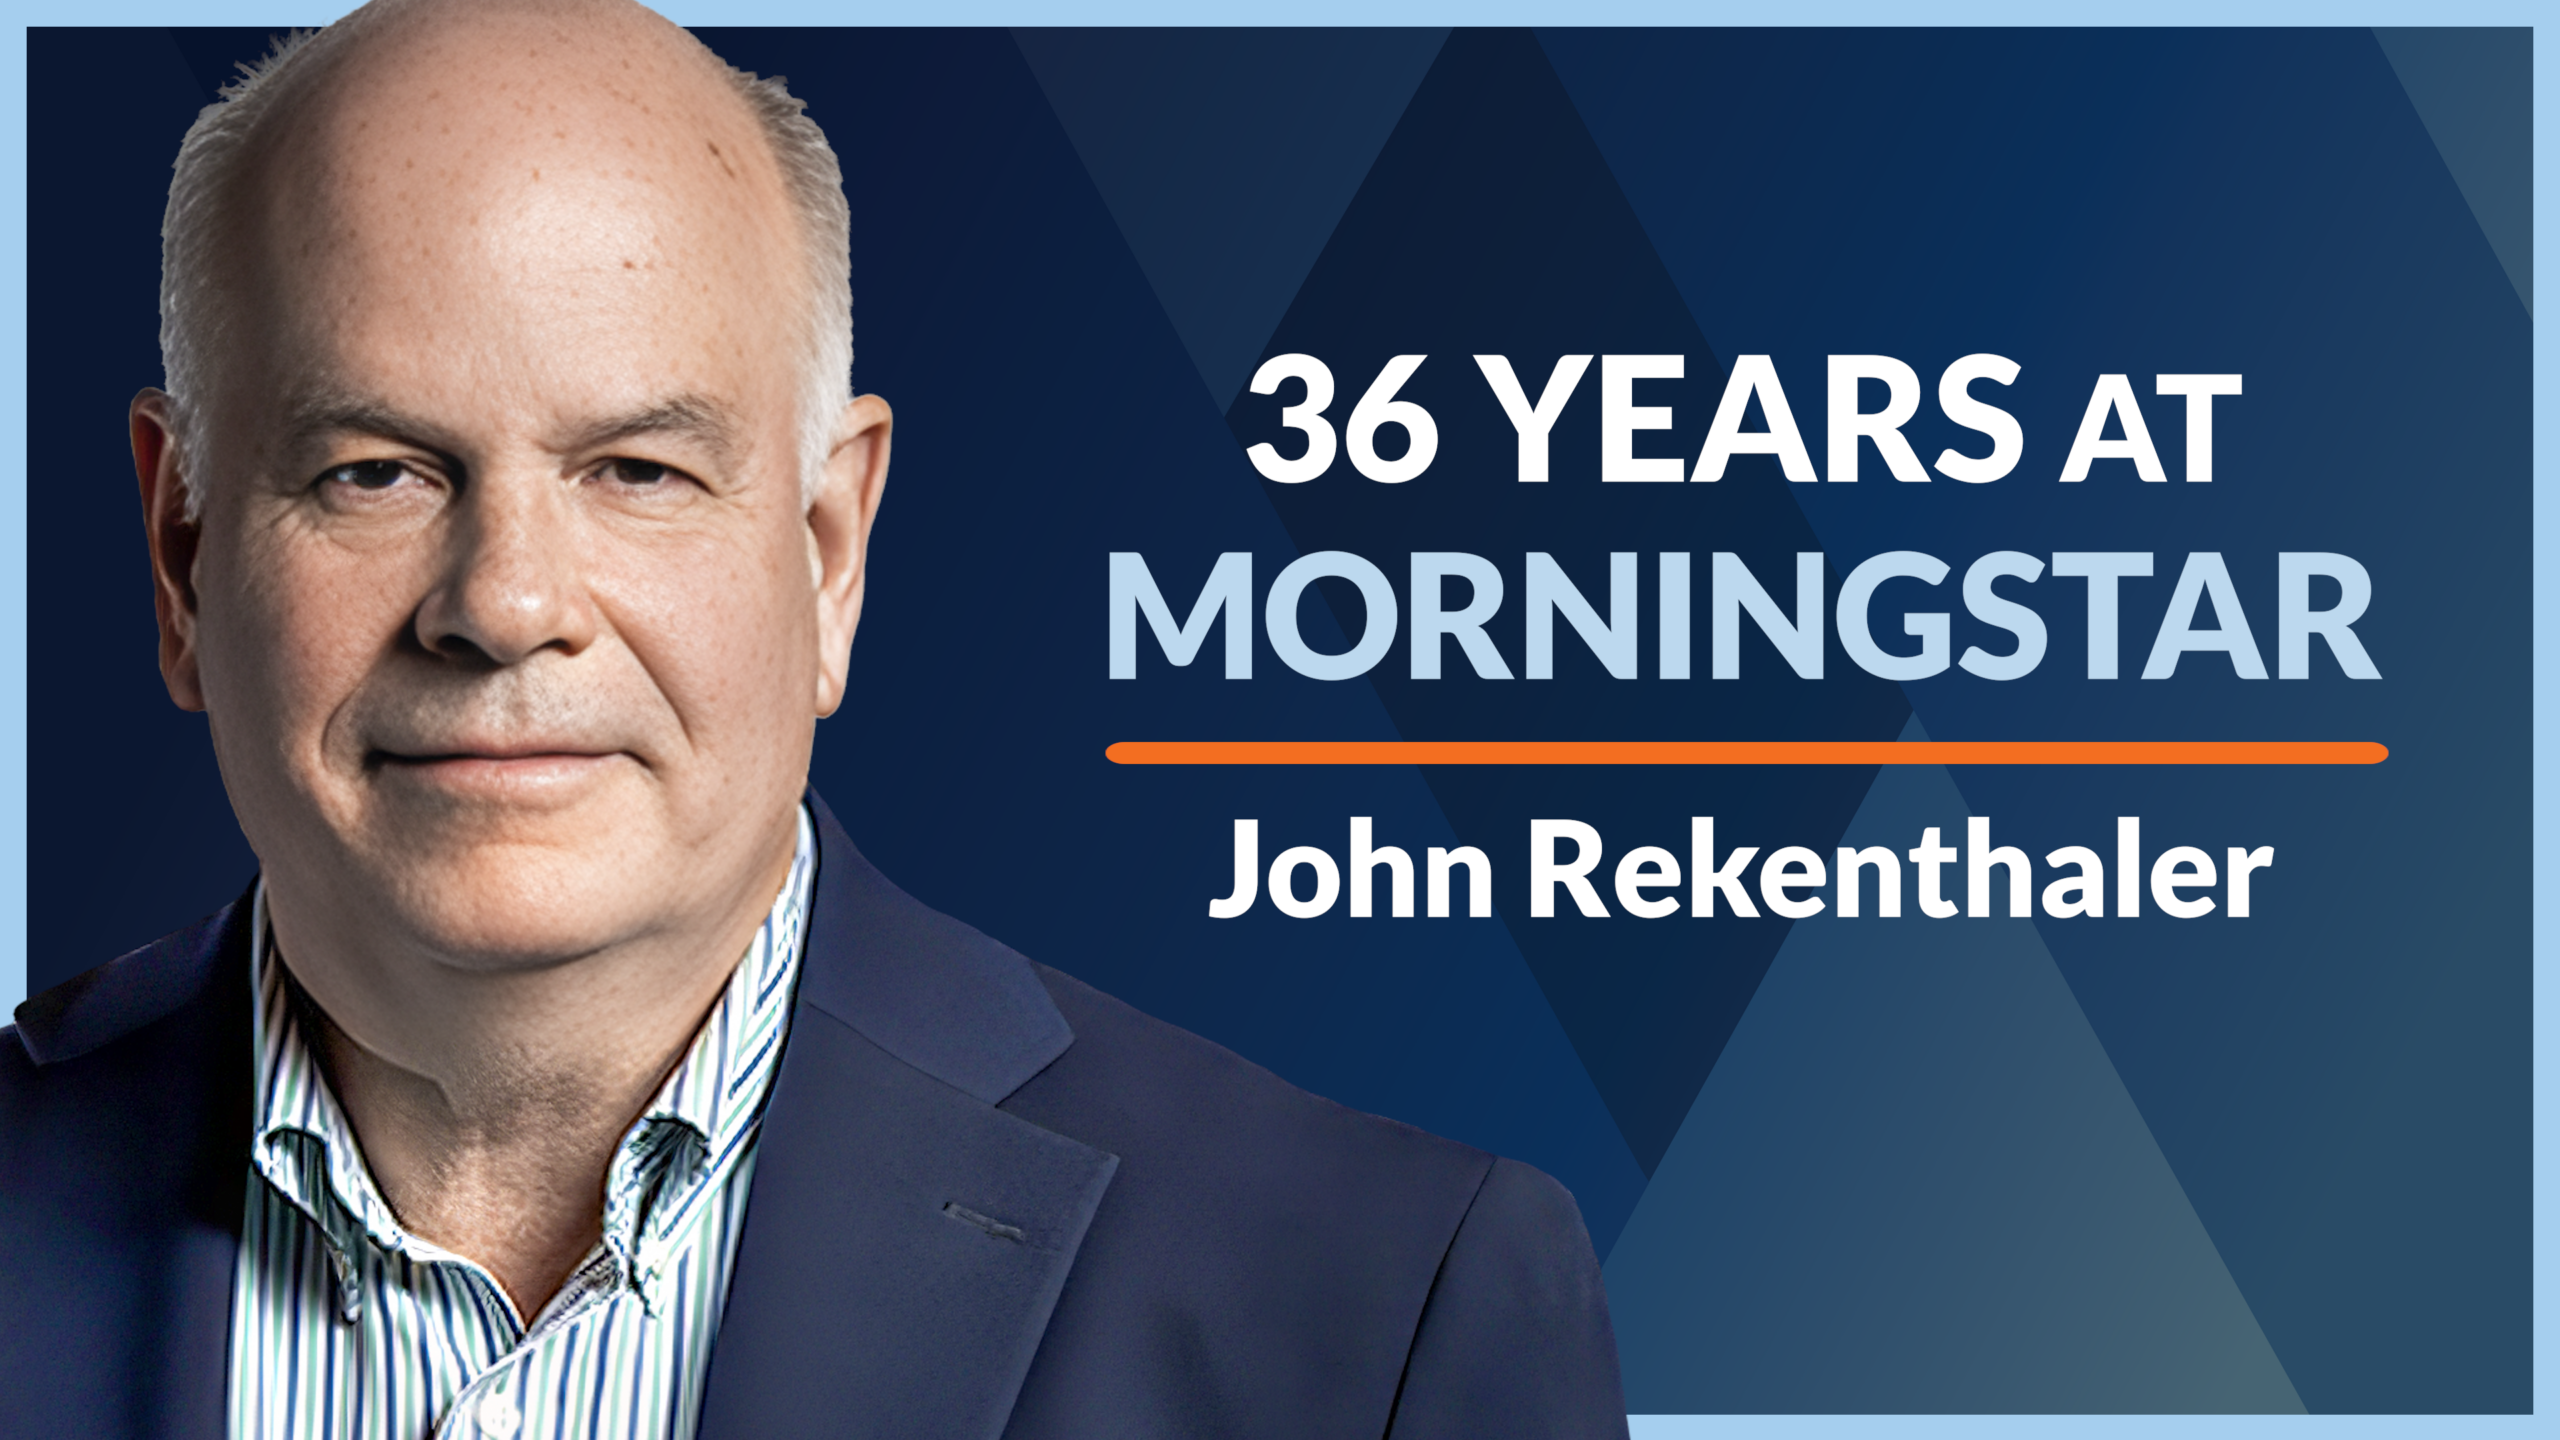
Today, we are talking to John Rekenthaler, a 36-year veteran and former VP of Research at Morningstar and the man behind the famous Rekenthaler Report. He is sharing the lessons he has learned from his decades in the industry. We cover topics like what matters most for people in the accumulation phase, Social Security timing, TIPS, tilts, and private investments.


How Index Funds Changed Investing and Wall Street
The rise of index funds has fundamentally reshaped investing over the last 50 years. When John Reckenthaler started at Morningstar in 1988, Vanguard was not even among the 10 largest fund companies. Mutual funds were largely products that were sold rather than bought, often through captive brokers and financial advisors charging loads. The assumption was that the firms controlling distribution, marketing, and brand recognition would dominate. Low-cost companies like Vanguard seemed destined to remain niche players because relatively few investors were finding and buying funds directly.
That changed dramatically as investors and advisors became more aware of the impact of costs on long-term performance. Fund expenses that once commonly exceeded 1% have fallen to a fraction of that for many investors today. High-cost funds still exist, but that is generally not where investor dollars are flowing. The largest providers can use enormous scale to offer broad diversification at extremely low prices, while smaller investment companies often try to compete by doing the opposite. They create more complicated, differentiated products that can justify higher fees. Complexity can be an effective marketing strategy, but it does not necessarily translate into better investment results.
John said decades of analyzing investments taught him to be skeptical when sophisticated strategies are presented as having obvious advantages with little discussion of their weaknesses. Portfolio managers are often intelligent, well-intentioned people, but they are also selling something. His MBA at the University of Chicago helped add academic rigor to what he had already learned through years at Morningstar, including formal exposure to efficient market theory and finance. His experience interviewing portfolio managers taught him to listen carefully for what was missing from the pitch and understand the circumstances in which an attractive strategy might fail.
That skepticism does not mean Wall Street provides no value. John said he views the financial industry from a middle ground. There are expensive products, gimmicky ETFs, complicated strategies, and investments that primarily benefit those selling them. At the same time, financial markets have given ordinary people extraordinary access to ownership. Someone can now own virtually every publicly traded company in the world almost instantly and at essentially no cost. Equity ownership is one of the great wealth-building opportunities available to individual investors. Wall Street provides much of the infrastructure that allows companies to raise capital and ordinary investors to participate in the profits those businesses create.
More information here:- Managers Don’t Beat Markets (Why Index Funds Are the Best Way to Invest in the Stock Market)
- 10 Unsung Benefits of Index Funds
What Actually Matters in Building a Portfolio
Despite concerns that stocks have become too popular or expensive, John does not believe investors should abandon equities. He has heard versions of that argument throughout his career, including when he entered the industry in 1988 and was told he had already missed the great stock market rally that began in 1982. There are pockets of speculation today, particularly around AI, but he does not see the overall market as comparable to extreme historical bubbles. Long-term equity returns may be more modest from current valuations, but stocks remain an important engine of long-term growth. At the same time, bonds have become significantly more attractive, with much higher yields than investors could obtain just a few years ago.
For investors who are still accumulating wealth, the most important principles remain remarkably simple. Save as much as possible, invest predominantly in broadly diversified equities, keep costs low, and avoid unnecessary trading. John sees little reason for most investors to make portfolios significantly more complicated than a total market or global stock index fund. Retirement introduces additional challenges because earned income is no longer available to compensate for mistakes or poor market performance, but the foundational principles remain the same. The amount invested, savings rate, diversification, costs, and investor behavior matter far more than endlessly optimizing small portfolio details.
That perspective also applies to factor investing. John does not believe investors need a small value tilt, although he sees little harm in having one. He would probably choose small value over large growth if forced to predict which would perform better over the next decade, in part because large growth companies have already performed so well and trade at relatively higher valuations. But he would not make a major portfolio bet on that prediction. Large growth’s success has not simply resulted from investors paying higher valuation multiples. Many of the largest companies have produced extraordinary earnings growth, and structural changes in the economy may allow dominant companies to remain dominant longer than historical patterns would suggest.
Higher yields have also made TIPS particularly compelling. A roughly 3% real yield from an inflation-protected government security represents an attractive alternative or complement to equities, especially when future stock returns may be lower than historical averages. John particularly likes TIPS relative to nominal Treasury bonds because the market’s implied inflation expectations create what he sees as an asymmetric tradeoff. If inflation comes in slightly below expectations, nominal bonds provide only a modest advantage. If inflation runs meaningfully higher, TIPS can provide substantially better protection. Investors still need to understand that TIPS are bonds and their market prices can fall sharply when real interest rates rise. They work best when investors are prepared to hold them to maturity rather than assuming their price will rise whenever inflation increases.
More information here:- Bonds Are as Attractive as They Have Been in 20 Years: What Should You Do About It?
- 6 Reasons to Have a High Early Savings Rate
Investing Beyond Public Markets and Building a Retirement That Works
Private investments make sense theoretically because investors should expect compensation for accepting illiquidity, reduced transparency, and additional complexity. In practice, capturing that premium can be difficult. Public markets provide daily liquidity, transparent pricing, extremely low costs, and extensive independent analysis. Much of that disappears with private equity, private credit, private real estate, and investments in smaller private businesses. The investor is often left evaluating an opportunity primarily through information supplied by the person selling it. Studies of alternative investments have also shown that potential excess returns can be consumed by manager fees. John has seen enough disappointing outcomes that he would treat private investments more like optional “house money” than something every investor needs to build a complete portfolio.
His own retirement portfolio reflects that preference for simplicity. At 65, John remains heavily invested in equities because he has a long time horizon, feels comfortable with stock market volatility, and has an annual withdrawal rate of only about 2.5%. Even if his portfolio fell by a third, his spending rate would rise to only around 4%. He also expects some of his wealth may eventually go to charity rather than being entirely consumed during his lifetime. Most of his taxable portfolio consists of individual stocks or a total stock market index fund, which allows him to control when capital gains are realized and keeps the portfolio highly tax-efficient. He owns some TIPS in an IRA, but he has not built an elaborate TIPS ladder, accumulated a huge cash reserve, or purchased annuities. He plans to delay Social Security until 70, and he is considering Roth conversions during the years between retirement and Social Security.
Retirement has also reinforced the idea that financial optimization should serve the life someone actually wants. John and his wife moved from the Chicago area to New York City even though doing so increased their cost of living and taxes. They wanted the experience of living in New York and decided the additional expense was worth it. He applies the familiar warning against letting the tax tail wag the dog—not only to investment decisions but also to lifestyle choices. Retirement does not have to mean minimizing expenses or relocating to the lowest-tax state. Once financial independence has been achieved, money can be used deliberately to create the retirement someone actually wants.
The final challenge is maintaining purpose and avoiding behavioral mistakes along the way. John has spent retirement reading, taking classes, traveling, exploring New York, staying engaged with investing, and planning a new blog focused more broadly on economics and politics. He now wants to give that work more structure and treat it more like a job. He also warns investors about the “bear market trap.” An investor sells during a downturn, the market begins recovering, and instead of admitting the mistake and reinvesting, the investor waits for prices to fall again so the original decision can feel justified. That can turn one mistake into two. He suggests establishing a predetermined rule for getting back into the market if it rises by a certain amount. He used a similar approach after the financial crisis, eventually investing cash after the market had already recovered about 15%. Missing the very bottom mattered far less than getting the money invested and participating in the long recovery that followed.
To learn more from this episode, read the WCI podcast transcript below.
Sponsor
Today’s episode is brought to us by SoFi®, the folks who help you get your money right. Paying off student debt quickly and getting your finances back on track isn’t easy, but that’s where SoFi can help—it has exclusive, low rates designed to help medical residents refinance student loans—and that could end up saving you thousands of dollars, helping you get out of student debt sooner. SoFi also offers the ability to lower your payments to just $100 a month* while you’re still in residency. And if you’re already out of residency, SoFi’s got you covered there, too.
For more information, go to sofi.com/whitecoatinvestor.
SoFi Student Loans are originated by SoFi Bank, N.A. Member FDIC. Additional terms and conditions apply. NMLS 696891
Milestones to Millionaire
#297 — $170,000 Net Worth as a Military Resident
Today, we’re talking with a second-year military resident who has already built a $170,000 net worth. Military doctors can get a major financial head start with little to no student loan debt and higher pay during residency, making those early years a great opportunity to save and invest aggressively. Programs like HPSP can be a fantastic way to pay for medical school, but only if you actually want to serve in the military.
To learn more from this episode, read the Milestones to Millionaire transcript below.
Sponsor: Mortar Group
Financial Boot Camp Podcast
Financial Boot Camp is our new 101 podcast. Whether you need to learn about disability insurance, the best way to negotiate a physician contract, or how to do a Backdoor Roth IRA, the Financial Boot Camp Podcast will cover all the basics. Every Tuesday, we publish an episode of this series that’s designed to get you comfortable with financial terms and concepts that you need to know as you begin your journey to financial freedom. You can also find an episode at the end of every Milestones to Millionaire podcast. This podcast will help get you up to speed and on your way in no time.
Donating to charity can be a meaningful way to support causes you care about, but donating appreciated investments instead of cash can make that giving more tax-efficient. When stocks, mutual funds, or other investments held for more than a year are donated directly to charity, you could deduct the full fair market value of the gift while avoiding the capital gains taxes that would have been owed if you sold the investment first.
After donating appreciated shares, you can use the cash you otherwise would have donated to repurchase the investment. This allows you to remain fully invested while effectively resetting your cost basis at a higher level. If a charity cannot accept securities directly, a Donor Advised Fund or similar charitable giving account can make the process easier, particularly for people who give regularly or make significant annual charitable contributions.
There are important rules to keep in mind when donating appreciated securities. The investments generally need to have been held for more than one year to receive a deduction for their full market value. Charitable deductions are subject to adjusted gross income limits, and you must itemize deductions to receive the federal tax benefit. Non-cash charitable contributions over $500 also generally require IRS Form 8283, so make sure the appropriate documentation is included with your tax return.
To learn more about donating appreciated shares, read the Financial Boot Camp transcript below.
WCI Podcast Transcript
INTRODUCTION
This is the White Coat Investor podcast where we help those who wear the white coat get a fair shake on Wall Street. We’ve been helping doctors and other high-income professionals stop doing dumb things with their money since 2011.
Dr. Jim Dahle:
Welcome back to the White Coat Investor podcast. It has been a wonderful fall here in Utah. It’s a wonderful time to be in Utah. It’s my favorite season here for sure. Nobody ever comes visits us in the fall, which is a real travesty, I think. Everybody comes in the blazing hot summer and goes to southern Utah and northern Arizona to see these national parks that we have.
The national parks are wonderful places, don’t get me wrong, but they’re way better in mid-October than they are in mid-July, I promise. And then, of course, in the winter, people come to ski in Utah, December through about March in northern Utah. We have some great ski resorts, and the skiing’s awesome, don’t get me wrong, but it’s not the fall. The fall in Utah is awesome, and so we’ve been out enjoying it and loving it.
But we today are inside helping you to become more financially literate, more financially disciplined, more financially successful. And the reason why is not because we love sitting inside, nor that we really need to make any more money. The reason why is because we know if we can help you to get your financial ducks in a row, you will be better at life. You will be a better doctor. You will be a better physician, a better parent, a better partner.
And then you’ll be able to focus on what really matters in life, building your practice, and taking care of your patients, and your own wellness, and your family, those things that really matter in life. And that’s why we’re here.
So thank you for being here with us. Without you, it’s not much of a podcast. You are a critical piece of the White Coat Investor community, and we thank you for what you’re doing.
Today’s episode is brought to us by SoFi, the folks who help you get your money right. Paying off student debt quickly and getting your finances back on track isn’t easy, but that’s where SoFi can help. They have exclusive low rates designed to help medical residents refinance student loans. That could end up saving you thousands of dollars, helping you get out of student debt sooner.
SoFi also offers the ability to lower your payments to just $100 a month while you’re still in residency. And if you’re already out of residency, SoFi’s got you covered there too. For more information, go to sofi.com/whitecoatinvestor.
SoFi student loans are originated by SoFi Bank, N.A. Member FDIC. Additional items and conditions apply. NMLS 696891.
We have a new program out. We call it the Resident Champion Program. So we’re launching two new things. One is a new book. Yes, that’s right. A fifth White Coat Investor book is called the White Coat Investor’s Guide for Residents. It’s now available for purchase on Amazon or at the White Coat Investor store. We especially recommend if you’re going to buy bulk copies of it that you go through the White Coat Investor store you can find on the website there.
But the second part is this Champion Program. Now, those of you who’ve been around for a long time know about the Student Champion Program. This is where we try to give a copy of the White Coat Investor’s Guide for Students to every first year medical, dental, etc. student in the country. We get it every year to something like 70% of the medical students. And so, we think that’s awesome.
Now, I’m not going to kid myself that they all take it immediately home and read every page of it. But I think very few of them throw it away. I think they put it on a shelf and when the time comes they pull it down from the shelf and they become financially literate and eventually financially disciplined and it helps them to be successful. So we’re trying to emulate that for residents with the resident book.
Now, the resident book is shorter. That’s deliberate. It’s a shorter book than the student book because residents don’t have that much time. And I’m just trying to get them the basics. The things you absolutely have to get done while you are in residency. That’s what the White Coat Investor’s Guide for Residents is all about. It helps them mostly get ready for that transition to attending.
Yes, there’s a few things you really do need to take care of during residency. But mostly it’s about getting ready for that most important year of their financial life, their first year out of training. And that right information at the right moment can be worth millions of dollars over the course of their career.
So, what do you do to learn more about this? You go to whitecoatinvestor.com/residentchampion. If you go to whitecoatinvestor.com/champion, that takes you to the student champion program. But whitecoatinvestor.com/residentchampion takes you to the resident program. And all we need is a volunteer from your first year resident class who will pass the books out to your co-residents. That’s it. That’s all you have to do as the champion. It’s super easy.
You give us your address. We make sure you’re actually in the program and how many residents are in the program. And we send you the books and you pass them out. That’s it. And usually if you’ll take a picture with some of your residents with the books, we’ll even send you some WCI swag. So it’s easy to do. And you get a free book too. Because you’re one of those residents.
But you get to also make a difference in the lives of your fellow residents. These are people you care about more than a whole lot of other people in life. And you can make them multimillionaires just by giving them this book. Millions of dollars times the number of residents in your class is the difference you could make by being a resident champion.
So thank you for doing that. Go to whitecoatinvestor.com/residentchampion to sign up. We’ll get you the books. You can pass them out. Super easy. Thank you so much for doing it.
All right. If nobody has told you thank you today for what you’re doing, especially if you’re on your way home from a hard day. You just told somebody they have cancer. You just told somebody their family member died or I don’t know whatever kind of terrible thing happened today. You got a notice of claim or something from an attorney. I have no idea. But if you had a rough day today, know that there are people out there that care about you. And we’re grateful for your dedication to your craft and what you’ve been working so hard to accomplish both in your personal life and in your professional life.
QUOTE OF THE DAY
Dr. Jim Dahle:
Our quote of the day today comes from John Roan, who said, “If you are not willing to risk the unusual, you will have to settle for the ordinary.”
All right. We’ve got a great interview today. I lined this up over dinner in New York City at a recent outing I had out there. I had an invitation from Vanguard to come out and celebrate with them the 50th anniversary of the Index Fund. And I happened to sit at dinner next to John Reckenthaler. And he graciously accepted my invitation to come be a guest on our podcast. So let’s get him on the line and chat it up with him.
Our guest on the White Coat Investor podcast today is John Reckenthaler. John recently retired from Morningstar after 36 years there. He was one of their early hires. He was brought on as a mutual fund analyst in 1988, eventually rose to become the company’s vice president of research.
Things that you’ve been using for years were developed by John. Things like the star rating, the style box. He helped launch the retirement business, but he’s probably best known as the author of the Reckenthaler Report, which was an investment column on Morningstar.com, became one of the most popular and widely cited columns in investing and personal finance.
Originally educated at the University of Pennsylvania with an MBA from the University of Chicago, which for those who know about index fund investing, who know about passive investing, know why it’s so significant to have been associated with the University of Chicago back in those days. But, John, welcome to the White Coat Investor podcast.
John Reckenthaler:
Good to be here, Jim, and virtually and to see you again, again, virtually.
Dr. Jim Dahle:
Yeah, we met face to face just a few weeks ago in New York City. I was out there for an event put on by the New York Stock Exchange and Vanguard. It was basically a celebration of the 50th anniversary of the index fund. John, tell us a little bit about that event and your thoughts about it now, having participated in it and seeing it in the rearview mirror by a few weeks.
John Reckenthaler:
It was my first time on the New York Stock Exchange floor, which is kind of silly given that I have been in New York. I live in New York City now. I moved there three and a half years ago, but I have three and a half years to get down there. And I walked by there all the time, but I never really thought about doing so.
Of course, as you realize, it’s not what the New York Stock Exchange floor used to look like. I think at one time it looked like in the movie Trading Places the commodities where they’re screaming and they’ve got arms up. Now it’s like there’s nothing going on. They don’t even hit the opening bell; sort of nobody hits it, actually. But when the opening bell is rung by some kind of mechanical or electronic means, the floor looks as it did before.
But the event, it was the 50th anniversary of the index fund. And each day they have an honorary bell ringing as far as I know of the Stock Exchange. I was honored to be invited and easy enough for me to get down there.
Dr. Jim Dahle:
Yeah, very cool. It is shocking how quiet the floor of the New York Stock Exchange is. You look around and it seems like there’s 30 people monitoring about 12 computer screens each to keep things going. But it is not what you’ve seen in movies put together in the 80s and 90s of what you expect to see.
John Reckenthaler:
Yeah, we don’t know if when a tree falls in a forest and no one’s around if it makes noise. But we do know that electronic traders don’t make noises. Not that you can hear. It’s very silent.
HOW INDEX FUNDS CHANGED INVESTING AND WALL STREET
Dr. Jim Dahle:
Yeah, very cool. All right. Well, 50 years, 50 years of the index fund. It’s pretty momentous that Jack’s work on bringing the concept of an index fund to the public retail investor has made such a difference in our lives. What kind of a difference has the index fund made in your career and in your personal life as an investor?
John Reckenthaler:
Both, huge. For perspective, when I started at Morningstar in 1988, Vanguard was not a top 10 fund company in terms of assets under management. The biggest fund companies, well, Fidelity and American Funds, who are still around, were among the two biggest.
But a lot of them really disappeared or gone by the wayside. A lot of the wire houses, the big brokerage firms. You had Prudential, Shearson, those kinds of Merrill Lynch and so forth. The wire houses selling. And that was very much the idea was a mutual fund was something to be sold, not bought. There were relatively few direct investors.
And in most financial advisors, almost all were selling load funds. A lot of them were captive brokers through working through one of these distribution systems. The thought was that the mutual fund companies that controlled the distribution that had the marketing muscle and the brand were those who would succeed. And a company such as Vanguard or some of these other small ones that didn’t advertise. Few people would find them, but there would always be an afterthought.
Of course, things have greatly changed since then. And Morningstar played its part, but it was hardly the only company to do so. The light of publicity of performance and in particular of the effect that costs had on performance has just greatly changed.
Even many years later, after I started in 2001, I think it was 2000, there was a survey of financial advisors that one of the fund companies did. And the advisors at that time rated cost as the seventh most important item when selecting a fund. You would not find that today.
And because of that reason, because both financial advisors and the general public, people have become aware of the great effect of cost, the drag of expenses. The average price paid by investors for funds has come way down from over 1% on average for equity funds on an asset-weighted basis. When I started to close, probably close to 1.5%, 1.25% say, and close to 1% for bond funds down to just a fraction of that today. So that’s a huge change and clearly for the better for investors.
Dr. Jim Dahle:
Clearly, there are lots of high expense funds out there, but that’s not where the dollars are going. The dollars are accumulating in the low cost funds.
John Reckenthaler:
Yes, that’s right. I think the way to think of it as kind of a market analyst, which I do in part besides being covering investments, I think about the marketplace and how investment companies are trying to position themselves. There are a handful of the major vendors and we all know who they are besides Vanguard, State Street and Schwab and BlackRock and a few others that have the volume where they’re able to offer very, very low cost funds.
And then there’s everybody else on the outside trying to figure out a way to have somebody look at their wares, look at their goods. And the way to do that tends to be the opposite of what the big players are doing, which is to stand out. Don’t do something simple and cheap. Do something complicated and not cheap. You can collect higher fees. And the fact that it’s complicated means that you’re different. And you sell that. You sell on the difference. You sell on the complexity.
That’s always been true, by the way. When I started, gosh, 38 years ago now, it was almost 39 years ago because it was the start of the year in 1988. And one thing as I was new to the fund industry and looking at it was realizing that there were fund companies that were selling. We just keep things simple. And those that said, “We’ve got complex strategies that you can’t really understand, but we understand them. And because we’re smart enough to understand them, that’s an extra value that you’re going to get.”
And it took me a while through experience to learn that it was not a promise that you were going to do well by following if you were an investor. Because over the years, I would see this particular type of investment that seemed to be relatively foolproof because the portfolio managers would explain to you all the advantages of this strategy. And they wouldn’t spend much time at all of any of the disadvantages or the market conditions that might expose the strategy.
And at the start, I had trouble discerning the difference until I got more experience in the matter. And so did a lot of other people too. We were all learning together I think you could say. Morningstar was a very new company when I started. The truth is that we learned as we went and we became better analysts and better researchers over the years.
Dr. Jim Dahle:
One of the things I was shocked to learn in New York, one of the things that was new in the 1970s, besides index funds, was the concept of no-load mutual funds. And the Vanguard S&P 500 index fund actually had a load in the beginning. They charged a load. It was only for a few months. But it was interesting for me to learn that while it was one of the first no-load funds, it was not no-load when it was first rolled out. Did that surprise you at all?
John Reckenthaler:
It did, actually. And I’m ashamed to say I should know. And I’ve read several of the books of history of Vanguard and Bogle and so forth. But I must have skipped over that part, or it just got lost in my mind. It wasn’t for very long. But yes, Jack was raised in the era where there have always been a few no-load funds out there. But essentially, everything was sold with a load through advisors. Mutual funds weren’t directly purchased. And that was what he was when he’d been at Wellington. That’s in his previous career before he started Vanguard, or earlier in his career. That’s what he knew. But he quickly changed.
Funds are still mostly sold through advisors. They’re just done in a different way. Now it’s advisors generally having an asset-based fee and using no-load funds in them. Really, that part of the marketplace hasn’t changed.
People tend to think that there are a lot more direct investing these days because the funds are no-load or you have ETFs that are effectively no-load too. And there’s always discussion in the marketplace or discussion in the media by individual investors and for individual investors. But most monies that come into funds are directed through financial advisors. The people who have the most money tend to be those who are older and often approaching retirement or in retirement. And they have a lot to lose.
Dr. Jim Dahle:
One of the things I wanted to talk with you about was how getting your MBA at the University of Chicago, in particular, affected your views on investing in the proper way to invest?
John Reckenthaler:
I would say my experience at Morningstar probably did that more because by the time I was in the evening program at Booth, it’s now called Booth, the University of Chicago Business Program, because David Booth gave them $400 million. So if you give somebody $400 million, they’ll often put your name on something. I haven’t done that yet. And it seems unlikely that I will because I’ve got to get to the $400 million first.
But I went to the business school in the evening, started seven years into my career at Morningstar. So I had been working with investments a lot and had learned a lot of things. For me, I knew about concepts of efficient markets and so forth. It was still great to go and get the formalization. And I’d also done, by the way, the CFA program as well, financial analyst. I had a pretty good background, better than most incoming MBA students. It was still to get to take a formal finance class and pricing classes and so forth. It added rigor to what I do.
And that was helpful to have it in a structured fashion. I was also fortunate enough to see a 90-minute debate between Eugene Fama, one of the fathers of index funds and the concept of efficient investing, and Richard Thaler, who is a behavioral economist. And they both Nobel Prize winners. So, that’s something fun that you might get when you’re going to an MBA program at Chicago. You probably would not get it at other programs. And it was just around the corner from the office. So, hey, who’s complaining? Except for when I was paying the bills.
Dr. Jim Dahle:
Do you feel like it boosted your career a lot? Or do you think it was mostly, I don’t know, lack of a better term, recreational learning?
John Reckenthaler:
Recreational learning. I did it for myself. Morningstar, at the time, didn’t care about credentials. Now we tend, I say we, I don’t work there anymore. I retired two years ago, but it’s still we, when you’ve worked there that long, are hiring a lot more people who have MBAs and experience and so forth. And I guess you would say a more traditional.
We were still largely the mindset of a startup company then, where we didn’t necessarily have the luxury of going out and being able to recruit against better known companies and so forth for the standard degrees. So, we were used to just looking anywhere and everywhere to find people who seemed like they might be able to do the work without worrying so much about credentials.
So, I didn’t get promoted because I had an MBA. I was sitting next to Motorola engineers in my class who said they had to get their MBA so that they could move up in their career because the next step was management. They were told they couldn’t manage people until they got their MBA. It wasn’t that situation. I was doing it for myself.
I did it actually largely because I was interviewing portfolio managers all the time who had MBAs and I didn’t want to feel like I was at a disadvantage to them, that they knew something I didn’t, that I could pull something over on me. You need to be skeptical as an analyst. You need to have that mindset. What are they saying that maybe there’s more to be said?
Because look, most people are good people and most portfolio managers, I like them, the ones that I’ve met. But still, this is a business opportunity for them when you’re interviewing them and you’re doing research and you’re writing about them as an independent analyst. And naturally, just as chief executive officers do when they’re talking about their company, there’s an element of pitch involved. So I wanted to be able to read through that as best as possible.
Dr. Jim Dahle:
What did you learn about the financial services industry and the way it operates and how it should be viewed by the individual investor in your 36 years there at Morningstar, mostly as an analyst?
John Reckenthaler:
I think you have to place me in the middle ground on this. You hear people that say all of Wall Street is just awful. And there’s a lot of consumer complaints and Wall Street tends to be a villain politically, actually really from both parties at times, certainly Democrats, but even Republicans at times.
There’s not a lot of sympathy for Wall Street and in media portrayals. I’ve already talked about it. There are a lot of players out there who are going to give you an inferior product, say with mutual funds, who will charge more and give you a strategy that’s complicated, but probably not going to be successful. They’re trying to make money. They’re trying to run a business and that’s the best opportunity they have. They’re not evil. It’s just that’s their best chance for success is giving you something that’s not that great.
But also Wall Street has done so many processes. The mutual fund industry is a good industry as far as the financial industry goes. I’ve tried to deal with impact in other aspects of my life with insurance companies on things. Oh, that’s a whole different. They’re very secretive. They’re not happy about having people inquire into their business.
Whereas mutual fund companies when Morningstar started, Joe Mansueto, the company’s founder, he was a nobody. He just is a 25-year-old guy who quit his job and said, “Oh, he’s an entrepreneur. I’m going to be an entrepreneur. I’m going to start a mutual fund database.”
And he wrote to all these fund companies, please send me all the histories of your funds, all your prices, all this, that. They did. That’s how he was able to assemble his database. So it’s always been an industry that’s been quite open. And I respect that. And it’s an industry that’s improved itself, too.
Dr. Jim Dahle:
It does get villainized. Make the counter-argument. What has Wall Street done for us as Americans, as citizens of the world that we would not have had there never been this Wall Street industry bringing companies to market and allowing us to share in that wealth creation process?
John Reckenthaler:
Well no, that’s right up my alley. I come from a family, Jim, nobody was an investor. I come from a family that was on one side were just guys with jobs, high school degrees and traveling salesmen and so forth. And back in the day when you got a little money and you put it in a bank or you hoped you worked for a company long enough where they gave you a pension.
And the other side of my family were school teachers, public workers and so forth, pension minds. Nobody invested. They never understood the power of ownership. In a way, they didn’t really understand the power of capitalism. And Wall Street is part of the mechanism that makes companies public, makes securities available and so forth. I’ve been an equity shareholder since one month after I started a Morningstar. And basically with my first paycheck, I put some money into an IRA and into a stock fund, which I still own today.
I’m a little bit of a Johnny Appleseed evangelical on the benefits of being an equity shareholder and ownership, because I’ve seen the power that it has. And the reality is companies, despite people’s complaints, and Lord knows everybody’s got complaints about the system and so forth and what could be better. This nation does very, very well at hosting companies that build big and profitable businesses.
Capitalism is very much thriving and ownership and participating and being on the capital side of that, that’s the way to make money, whether you’re owning a small business or shares directly or owning shares of a larger business. Ownership is what it’s about. Wall Street, it wouldn’t happen the same way without an intermediary, without various functions that make this relatively seamless. And think how cheap it is. We can buy a fund for two basis points, essentially free.
Dr. Jim Dahle:
Practically free. You can buy every publicly traded company in the world in 30 seconds essentially for no cost.
John Reckenthaler:
Yeah, I sound like I’m up here on a Sunday morning now. Something like that. Preaching a sermon, but I believe it. I do. And I say there are, I see the other side. One of my lines, or one of the things I think about exchange traded funds, they’re like the little girl with a curl. When they’re good, they’re very good, but when they’re bad, they’re horrible.
And there’s some just terrible exchange funds out there. Leveraged funds and gimmicky income funds, because it’s not really income, they’re paying back the principal. Crypto funds. I guess if you’re going to own crypto, maybe the fund is the way to go, but whether you should own crypto is a different issue. There’s lots of bad stuff out there. So I don’t want to overstate the case. But as we talked about earlier, most people have their money in the good stuff.
Dr. Jim Dahle:
When you came into the industry, it had just been a few years since… There’s a famous Newsweek article that the front page said “The Death of Equities.”
John Reckenthaler:
1982. Yeah, this was six years later.
Dr. Jim Dahle:
Yeah. And yet during your career, equities have become the preferred way for Americans to invest to the point now where you almost can’t talk people into buying bonds, especially anybody who looks at past returns that include 2022. They’re like, why would I buy bonds? I might as well just stick it in the bank. I’m going to come out ahead. Has the pendulum swung too far? Clearly in 1982, it swung too far against equity. Has it now swung too far in favor of equity?
John Reckenthaler:
I don’t think so. For perspective, when I started, people told me that I was too late. There’d been the rally since 1982. The gains were done. People were making the argument in 1988 that the pendulum had swung against equities. I was looking in the rearview mirror if I thought that equities were going to be that much better than bonds.
And I’ve heard that for almost 40 years now. And when I look at prices on the stock market today, by and large, we can set aside AI stocks in certain areas of speculation. I don’t think these prices seem crazy. There are a whole lot of solid companies out there selling 20 times earnings. I don’t think 20 times earnings is a reasonable price to pay 5% earnings yield for stock.
Today’s market doesn’t worry me in the same sense I felt in 1988, 1999, 2000. It might be a little heated. We might be in for some mediocre five-year return, say, on equities, but for the long-term investor, I don’t think this is Japan 1989 and a 30-year thing going.
On the other hand, bonds have become more attractive. 5.5% yield now you’re getting on Treasuries. You can get 6.5% or so on decent quality investment-grade corporates. That’s pretty good. And TIPS yields, if you want to do the inflation-protected route, are up to about 3% real yields. I wouldn’t say don’t own equities or that they become overrated, but it’s true that bonds have become more attractive relative to equities. That’s true, without question. And I also would agree that bonds belong in a lot of most portfolios, maybe quite a few bonds, depending on the circumstances.
WHAT ACTUALLY MATTERS IN BUILDING A PORTFOLIO
Dr. Jim Dahle:
Let’s talk a little bit about what really matters. Most listeners to this show are professionals, high-income professionals. Some are business owners, and there’s engineers and doctors and lawyers and accountants and financial advisors and all kinds of people listening to the show. But what most of them have in common is a relatively high income.
One thing I try to focus people on a lot is what really matters. There’s so many details when it comes to investing in personal finance or Wall Street. You can get lost in the details. If you had to pick three to five things that actually matter to an individual in their financial life, what would those things be?
John Reckenthaler:
I don’t think things I’ll say will be surprising. For the people in accumulation, save as much as possible, put it predominantly into equities, keep your costs low, don’t trade. Vanguard total market or Vanguard global, whatever, fine. You don’t have to get more complicated than that.
As you know, and I’m sure your listeners know and your audience knows, again, in retirement, when you’re withdrawing money from your portfolio and when you don’t have the human capital or income coming in from your work endeavors to support maybe mistakes that are made or problems with your portfolio, things do get more complicated and the advice isn’t so simple.
But those things still matters to keep costs down and trade infrequently and so forth, but it becomes a little more complicated. But I think it’s really quite simple. What matters is just put the money to work, get a lot of money and put it to work efficiently by, again, I remain a believer in the stock broadly, the stock market, not trying to cherry pick. I wouldn’t want to play with AI stocks unless it was dabbling with a corner of the portfolio on the side for fun.
There’s nothing wrong with having a little fun with house money, but I’ve seen the mistakes made over the years. I recall in 1999, talking to a plan sponsor about their 401(k) plan and they were saying that they had a sophisticated group of investors, airline pilots in this case, not normal investors. So they wanted to get an internet fund into their 401(k) plan.
Dr. Jim Dahle:
Perfect timing, 1999, huh?
John Reckenthaler:
Yeah, 1999. Even at the time, and this is before they’d crashed, I was like, I don’t really think this is what you want to do and I don’t think this is my definition of sophisticated either, but don’t go down that path.
Dr. Jim Dahle:
I have seen so many people talking about that and all I can think about is 1999, 1999, 1999, and we want an AI fund, we want a tech fund, we want a growth fund. Very few people are talking all that much about value. It’s been a little bit of a resurgence this year in small value stocks. They’ve actually outperformed the overall market for the first time in quite a while, actually.
What are your thoughts on this sort of factor investing, this tilting a portfolio towards small value? Is the pendulum going to swing back? Do you have to even know that to make this sort of a decision of whether it’s worth having a little more complexity, paying a little bit more in costs in order to have a small value tilt in your portfolio?
John Reckenthaler:
I don’t think people need to have a small value tilt in their portfolio. I don’t think they need to add that complexity. I don’t think there’s much wrong with it either because in the grand scheme of things, being in equities and having a lot of money put to work is by far more important than the portfolio details.
I would guess that over the next decade, say, small value would probably outperform the large growth stocks because the large growth stocks have done so well and are relatively expensive. As I said before, I don’t think this is a bubble. There’s some good reasons why the large growth stocks have done so well. Those businesses have done extremely well.
Dr. Jim Dahle:
Most profitable corporations in the history of mankind.
John Reckenthaler:
By far. I wouldn’t bet against large growth and the giant growth companies in that sense. If I had to bet, if you said, John, small value or large growth, which is going to do better in the next 10 years, I would say small value, but it’s not like I would bet my entire portfolio or even a large stake on that.
Dr. Jim Dahle:
Yeah. I would have made that bet five years ago and I would have been wrong.
John Reckenthaler:
Or 10 years ago. 10 years ago, I wrote about this very topic and I said, don’t count large growth out and people were doing so. Because I was looking at the performance of these things. I said, they performed great, but largely the returns, it’s not been multiple from PE expansion in their price multiples and the amount of money people want to pay for. It’s been from expansion of the denominator of their earnings.
It’s a whole different discussion. I do think there’s a thesis to be made about how economic conditions have somewhat changed and the really giant companies are likely to have become even more giant. And how the rich have become richer is true, not only among individuals, and we’ve seen the growing inequality of wealth kind of charts and so forth among individuals, but also among corporations.
That’s a whole long, long discussion. Just saying there are factors to consider when besides just a simple history or looking at a chart and saying, “Wow, this stuff has been down for so long, it’s got bound to come back up, or this has been successful for so long, things have got to change.” That’s a concern. It’s a possibility. It’s a data item, but it’s not the only one. That was a long-winded answer. Sorry, I do that sometimes.
Dr. Jim Dahle:
No, no, it’s perfect. You got into exactly what I was hoping to explore, so I appreciate that. A little bit of a change of a topic, you had alluded to the fact that bond yields are dramatically more attractive now, particularly on the inflation index side.
There are a lot of informed investors that are looking at TIPS in a whole new way. They find these treasury inflation-protected securities to be very attractive right now with, on the longer term, yields in the 3% range, and going, “Well, why bother with equities when I can essentially lock in an awesome retirement just building a TIPS ladder at this point?” How should people be thinking about TIPS in their portfolios, and is that different now that yields are higher?
John Reckenthaler:
Yeah. 3% real yield, which is what TIPS pay, is very high for an inflation-protected security. Stocks historically have had quite a bit more of an annual real yield in the 7% range, but I don’t think any of us think that necessarily will be sustained given where values have become higher.
I’m still a stock bull, but I’m thinking maybe more 5% to 6% long-term. 3% for TIPS, which are absolutely government-guaranteed, recession-proofed, and all that sort of thing, that’s attractive as well as being great counterbalance for whatever equities you have.
I talked about nominal bond yields being 5.5%, but TIPS yield at 3%. What that means is the expectation is that inflation will average 2.5%. That’s how the numbers work. If inflation is more than 2.5%, you’re better off long-term holding TIPS rather than a nominal bond. To me, that’s an easy bet to make. You’d rather be in TIPS. I don’t know where inflation is going to be.
Dr. Jim Dahle:
But it’s currently over 2.5%.
John Reckenthaler:
It’s currently over 2.5%, and you don’t have to be, and I’m not a doomsday scenario person to think of inflation being 4% or 5% or even potentially spikes higher than that over a fairly long period of time. We’ve had that in the past in our history. In which case, this bet has worked spectacularly against you. If inflation is 2% over the next 20 years or 10 years rather than 2.5%, how much have you lost by being in TIPS? It seems to me that the bet’s asymmetrical. If you’re right and you own nominal bonds, you don’t get much extra benefit. If you’re wrong, you can get really whacked. I would definitely side with TIPS.
The thing with them, as you know, these are buy-and-hold investments in 2022. Inflation rose dramatically, and TIPS prices got crushed, which surprised a lot of people because you think, hey, these are supposed to be inflation-adjusted. They are inflation-adjusted investments, but because of the mechanics of how real interest rates work, it can happen where, in fact, you have, during times of spiking inflation, the security that you owned for inflation protection actually goes down in price, and you have to hold it till maturity for that bet to pay off.
Dr. Jim Dahle:
They’re inflation bonds, but the key part is they’re bonds more than they’re inflation, and bonds react to rising interest rates.
John Reckenthaler:
I think they’re difficult for people to own. I don’t like the construction of them. I think that, ideally, the government would have figured out something that pays you, sort of, I guess iBonds would work more like that, but that pays you as inflation rises and would help to keep people in these things and owning them, because ownership of TIPS is not very high, given really how attractive they are, and I think that’s because they’re so counterintuitive.
INVESTING BEYOND PUBLIC MARKETS AND BUILDING A RETIREMENT THAT WORKS
Dr. Jim Dahle:
Now, a lot of your analysis has focused on publicly traded securities, both stocks and bonds, mutual funds, etc., and of course, that’s the easiest thing to make a database of, which Morningstar has, as near as I can tell, the greatest database of publicly traded securities available out there.
John Reckenthaler:
I’m willing to echo that. I don’t know if it’s true, but I like the sound of it.
Dr. Jim Dahle:
Yeah, but there is these other investments out there. Before SpaceX went publicly traded, it was a private company. You’re seeing companies come off the stock exchange from time to time and become private. The vast majority of real estate investments are not publicly traded. There are all kinds of small and medium-sized companies across the country that are not publicly traded.
What role do you see for private investments in an investor’s portfolio? Is there a role? Is it only for particularly wealthy people? Should everybody avoid them completely? What are your thoughts on investing outside of these very liquid publicly traded securities that are essentially mark-to-market every day?
John Reckenthaler:
Well, they make sense in theory. It’s equities and say with the owning an ETF, mark-to-market, immediate liquidity, extremely low cost, transparency of what you own, independent parties like Morningstar and others looking at, evaluating, third-party analysis. That all disappears and you end up in the situation that I’ve discussed, which is somebody on the other side of the table who has something to sell. It may be something good to sell, but it may not be something good to sell, good for you to own, and it’s difficult to make that call.
I should point out Morningstar actually is involved with private equities now because a few years ago, it bought a company called PitchBook, which is a leader in private equity information. Morningstar does have private equity information and has been adding that to its coverage and so forth. But many of the other things that you talk about that you mentioned, for example, real estate or small to mid-sized businesses, smaller businesses that say wouldn’t be in PitchBook’s database or private credit would be outside of not just Morningstar’s purview, but really almost any outside party’s purview.
So, unfortunately, I’d have to say I’ve seen more bad experiences than good experiences. My advice to people would be, again, think of this a bit as house money, not as your essential money. At this stage, I’m leery of the argument that this must be in your portfolio to have a complete portfolio. I would say have a complete portfolio, be in things that you know you can own cheaply and that are liquid. And if you want to add additional level of involvement, kind of do so with eyes wide open going in.
Dr. Jim Dahle:
Theoretically, there should be some sort of a premium offered for being a liquid, for having less transparency. Does that premium maybe just accrue to the managers, to the people selling these investments? Or is it possible for the individual investor to capture it as well?
John Reckenthaler:
It’s possible, but often it doesn’t accrue to the individual managers. Many studies of hedge funds and other such funds have determined that the alpha pretty much is swallowed up by the fees. Also, in theory, extremely illiquid stocks will give you a premium because of the lack of liquidity.
But when people have done studies of the performance of those stocks, they haven’t necessarily found that. In fact, they found that some of the least liquid, smallest fringe stocks, if you bought a pool of them, you would have done poorly because it was kind of garbage. There’s a lot of fraud involved with that too. So in theory, yes. In practice, trickier.
Dr. Jim Dahle:
All right. Let’s turn a little bit. You’re a relatively new retiree. You’re somebody who spent your whole career analyzing investments. You’re savvy when it comes to finances and investing. Let’s talk a little bit about how you decided to retire, how you’ve decided to decumulate, how you’re spending your retirement money, and maybe a little bit about what your actual decumulation plan looks like.
John Reckenthaler:
Yeah, my decumulation plan is basically, I’m in equities largely. And that’s partly because of my belief in equities, partly because I can afford to be in equities. My annual withdrawal spending rate’s about 2.5%. I have room for error. If the portfolio drops by a third, I’m at a 4% annual spending rate. And by then, I think equity prices would be attractive enough where they probably would rise from that point as well. And I just started my retirement. I’m 65. I’m hoping to live another couple of decades at least. Maybe we can go for three.
So, I consider myself still to have a relatively long-term time horizon. And I’m thinking about charitable giving down the line. I’m not trying to eke out every penny of my portfolio for current existence. I’m thinking about those other issues too.
And finally, we all have different risk tolerances and comfort levels. I’ve always been comfortable with stocks. And I’ve not really been too bothered when I’ve been hammered periodically in the stock market. All those things put together, I’m a good candidate to be high in equities. But again, that’s a personal thing.
Dr. Jim Dahle:
Yeah. No complicated TIPS ladder, not purchasing a bunch of single premium immediate annuities, no huge cash stash to weather sequence of returns risk, any of that stuff.
John Reckenthaler:
Yeah. I’ve looked into all that stuff. I do own TIPS in my… Not a ladder. I just bought a 10-year TIPS. Unfortunately, they were at 2%. I said, “Oh, 2% real yield is great. Now it’s 3%. I should have waited in my IRA.” So I have it there. But most of my money is in a taxable account. And there, of course, the concern is taxes. And so, basically, I have either stocks or an index fund, VTI, Vanguard’s total stock market.
Essentially, I have no capital gains unless I sell something and not much income these days, because companies tend to be repurchasing their stock rather than paying dividends. So it’s almost a tax-free portfolio until I choose to take out the gains. So it’s pretty tax-efficient that way.
Dr. Jim Dahle:
What did you decide to do with social security?
John Reckenthaler:
Oh, I should have asked you. I read everything. I’m not an expert on social security stuff. I’m just waiting till 70. Is that the right thing to do?
Dr. Jim Dahle:
Usually. Usually, if you’re healthy and you’re the higher earner in the couple, that’s usually the right thing to do.
John Reckenthaler:
Well, there you go. I should ask you about other strategies. What should I be doing about IRA and Roth IRA and so forth? That one’s always confused me.
Dr. Jim Dahle:
Oh, man. The hardest question in personal finance of how much and when to do Roth conversions.
John Reckenthaler:
Well, I’ll subscribe and you’ll tell me.
Dr. Jim Dahle:
You’re definitely in those years to think about it.
John Reckenthaler:
Yeah, I am thinking about it.
Dr. Jim Dahle:
The main question is who’s going to pull the money out of that account and what’s their tax rate going to be when they do it? Obviously, you don’t want to do a Roth conversion on money that’s going to charity. That’d be stupid. The charity’s pulling it out at 0%. Or if you’re leaving it to one of your heirs that’s going to be a lower tax bracket than you, it’s stupid to do a Roth conversion.
There’s certainly advantages to doing them. You’re in the prime of time. You’re between the prime time to be doing these in between retirement and when you start taking Social Security is definitely the Roth conversion years. It’s worth considering.
John Reckenthaler:
My background is investments and understanding, in particular, the fund marketplace and so forth, not necessarily in personal finance. I take advice there. I don’t give advice. I started a 529 plan for my granddaughter this year. There you go.
Dr. Jim Dahle:
There you go. Now, you did something unique among retirees. There are all kinds of people who retire from New York to Florida, for instance. You moved to a higher cost of living area to retire. Tell us a little bit about that decision and how it’s affected your finances and your retirement.
John Reckenthaler:
Sure. Morningstar is based in Chicago. My wife was born and raised in Chicago, lived there her whole life. I’d been there for 38 years since I came out in my mid-20s. We were empty nesters. I wasn’t quite retired at that stage. This was three and a half years ago. I retired two years ago. Of course, that was starting to bloom. We were thinking, where do we want to live? We’re city people. We were empty nesters in the suburbs. We were thinking about moving back into the city of Chicago. We looked at each other. My wife said, “Well, I know Chicago so well by now.” I really like big cities. For her, Chicago was a small city. We started talking about New York. Very quickly, we just said, “Let’s go do it.”
We make the big decisions quickly and the small decisions slowly. That was pretty much an overnight thing, really. Almost, just a few days. We tell people this, and about two-thirds of people look at you blankly trying to think of something polite to say. One-third say, “Oh, that’s great. I’d love to do that. I’d love to live in New York.” That’s personal taste. That’s our personal taste. Of course, I am paying more taxes. New York State taxes are pretty good size, but there’s New York City tax, too.
There’s the saying, “Don’t let the tax tail wag the dog.” Don’t let the tax tail wag your enjoyment, your lifestyle choices, too. I know I’m paying for the enjoyment that I get from this, not necessarily the enjoyment that you would get from this, but the enjoyment I get from this. I’m willing to pay it. I’m happy to pay it. That’s a fair trade. You get what you pay for, in my case. Again, that’s a personal thing.
I can understand why. I’ve got a friend. He’s moving from Illinois to Kentucky, Tennessee, wherever it is. One of those states has a much lower tax rate. Illinois isn’t even that high, but he wants lower, and people move to Florida for that. Of course, there’s the weather issue, too. Now, coming from Chicago, I think New York winters are like tropics.
Dr. Jim Dahle:
There’s a lot of truth to that. The other transition that’s tough in retirement, besides figuring out the finances and the decumulation plan and making sure you have enough and so on and so forth, is this concept of identity and purpose as you move out. You mentioned when we were eating dinner in New York that the difference you found now is you still work a lot. You work without getting paid for it now. That’s been the difference in moving into retirement. Tell us what you mean by that and what you’ve done to ensure you can maintain purpose in retirement.
John Reckenthaler:
No, that is a good question. When I say I work a lot, I’ve been dabbling a lot. I do want to change that and dabble less going forward. By dabbling, I mean I’ve been doing a lot of personal reading, taking some classes, great books and classes at the University of Chicago, traveling, jotting down notes for a blog, still communicating a lot about investments with people in various ways, writing notes and so forth. Seeing the city, we move to the city to do things, so doing city things, and visiting family.
All those kinds of things have kept me busy, but I am looking around and saying, I need to get more focused. This blog that I’m going to write about, which is going to be about economics and politics, has investments in it, but more broadly about economics and economic issues. I’m going to start focusing on that. Treat it like a job. I think it’s important. I haven’t done that yet. I think it will be useful, at least for me, to look at something as a job and actually set a schedule around it.
Dr. Jim Dahle:
Be careful what you do. I started a blog in 2011, and now there’s 20 plus of us working here.
John Reckenthaler:
Yeah. I don’t want employees. I’ve had employees. I had good employees, but still, you know how it goes. There are a set of issues that come with being a boss.
Dr. Jim Dahle:
Yeah, for sure. All right. Well, our time is short. What else do you think high-income professionals, doctors, etc., should know about investing and personal finance that maybe we haven’t covered today?
John Reckenthaler:
I guess the last thing I’d mention is what I call the bear market trap. Bear market trap is when a downturn frightens people or worries people or for some reason pushes them to sell securities. And they sell at the bottom or they sell low, and they start to realize they made a mistake. And they don’t want to acknowledge that mistake.
So, when the market goes back up, starts going back up, they wait. They want to wait for it to come back down again so they can buy at something close to the bottom or even ideally below what they sold at. So they feel like they didn’t make a mistake. I’ve seen people do that. I’ve seen portfolio managers do that over the years. And it’s disastrous. I thought this downturn was coming. I thought I was being smart by getting out at the right time. And the market just keeps climbing back, and you’re missing those gains, and you’re waiting for it. You’re just sitting there with the cash waiting to get back in.
I would set a rule. If you sell something during a downturn and you have cash, something I’m saying equities really, but if the stock market goes up 20% over time, could be the next two weeks or it could be the next two years, whatever it is, from there, get in.
Dr. Jim Dahle:
Make it so you only made one mistake and not two.
John Reckenthaler:
Make it so you only made one mistake, not two. And it doesn’t have to be. I just made up 20. It could be a different number. And I think back in 2008, the financial crisis, I didn’t sell, but for a strange reason I had a bunch of cash sitting around at the bottom of the market in 2008. I was worried. Warren Buffett was talking, and Warren Buffett is not a doomsday person. Warren Buffett was talking about maybe this is it. Maybe the Great Recession, the Great Depression second is coming. Our financial system is on the edge. I was not brave enough to put that cash to work in January 2009 or March 9th, I think 2009 was the bottom.
But in June, the market was up about 15%. I said, “You know what? I’m feeling like probably we’ve crossed the precipice. There are enough investors out there. I got the courage and I put that money to work.” Yeah, I missed the first 15%. You want to do the math since June 2009 of what that money has made. So yeah, make a small mistake, not a big mistake.
Dr. Jim Dahle:
Good advice. Well, we’ve been chatting with John Reckenthaler, now retiree is maybe his most important title, but previously vice president of research at Morningstar, still doing great work out there for the individual investor. John, thank you so much for your time today on the podcast.
John Reckenthaler:
Thank you very much. And I’ll go with grandfather is my best title right now.
Dr. Jim Dahle:
Awesome. Thank you for sharing that.
John Reckenthaler:
Thanks, Jim.
Dr. Jim Dahle:
I hope you enjoyed our interview as much today as I did making it. It’s always great to talk to people who have been influencing thought literally for decades about investing, about personal finance. And John has been out there fighting the good fight now for a long time. Retired now, but even in retirement, he has things he can help us about how to retire successfully. So, I hope you appreciated the lessons he shared.
Thanks for those of you who are leaving us five-star reviews. It really does help get the word out about this podcast. A recent one came in, this one from Gail who said, “My go-to financial podcast. I’ve been listening to this podcast since its inception. The more I listen, the more I learn and am inspired. I appreciate the diversity of invited guests and the positive messages and celebrations of those who are interviewed on Milestones to Millionaire. Dr. Dahle and staff are providing invaluable service. Thank you for all you do.” Five stars.
Thanks, Gail. It’s really nice of you to leave. But the important thing is not making us feel good about the work we’re doing here. The important thing is reviews help people find the podcast. And when they find the podcast, they get this information, they change their lives, they change their practices, they crush their burnout, and they help a hundred other people. And that’s what we’re trying to accomplish today. So thank you so much for leaving a review. It’s not much, it doesn’t take long, wherever you get your podcast, just put in a review. They’re always encouraging you to do it anyway. It only takes a few seconds, thanks to those of you who have done it.
SPONSOR
Dr. Jim Dahle:
As I mentioned at the beginning of the podcast, SoFi could help medical residents like you save thousands of dollars with exclusive rates and flexible terms for refinancing your student loans. Visit sofi.com/whitecoatinvestor to see all the promotions and offers they’ve got waiting for you.
SoFi student loans are originated by SoFi Bank, N.A. Member FDIC. Additional terms and conditions apply. NMLS 696891.
Keep your head up, your shoulders back. You’ve got this and we can help. We’ll see you next time on the White Coat Investor podcast.
DISCLAIMER
The White Coat Investor podcast is for your entertainment and information only and should not be considered financial, legal, tax, or investment advice. Investing involves risk, including the possible loss of principal. You should consult the appropriate professional for specific advice relating to your situation.
Milestones to Millionaire Transcript
INTRODUCTION
This is the White Coat Investor podcast Milestones to Millionaire – Celebrating stories of success along the journey to financial freedom.
Dr. Jim Dahle:
Welcome to the podcast.
Mortar Group is a premier real estate investment firm focused on multifamily properties in both ground-up and value-add projects in the competitive markets of New York City since the early 2000s. With over $300 million in asset center management and over 30 investments since inception, their fully integrated firm model allows Mortar to maximize efficiency and value across their investments in these niche markets.
Mortar leverages over two decades of experience in architecture, development, and asset management in their projects to build value and minimize risk for investors. Invest in tax-efficient, high-return, risk-adjusted strategies with Mortar Group at whitecoatinvestor.com/mortar.
All right, we have a cool event coming up. It’s totally free to you. Well, half of you. The other half aren’t invited. You see, this is a FEW event. FEW stands for the Financially Empowered Women. We have a live webinar, October 22nd, 06:00 P.M. Mountain. It’s going to be all about employer benefits. It’s going to be taught by some of the CFPs at White Coat Planning, Meredith Dean and Brenda Hill. It’s going to be awesome.
And you got to really understand this stuff. I’m shocked how few people actually understand what their employer is offering them, whether that’s HSA contributions, whether that’s 401(k)s, whether that’s health insurance and how it works, whether to use the PPO plan or the high-deductible health plan, whatever. All this employer benefits stuff, they’re going to go over on that webinar.
They’ll have an opportunity to ask questions. It’s a great opportunity to get together with your fellow women White Coat investors and enjoy an awesome evening. You can sign up for that at whitecoatinvestor.com/few.
We’ve got a great guest today. He is a military member, an officer, a captain, and is actually serving someplace I have served, which was pretty fun to realize, but let’s get him on the line and let’s talk about some of his successes and use them to inspire you to be successful.
INTERVIEW
Dr. Jim Dahle:
My guest today on the Milestones to Millionaire podcast is Matthew. Matthew, welcome to the podcast.
Matthew:
Thank you for having me. It’s an honor to be here.
Dr. Jim Dahle:
Okay. Tell us a little bit about you. Where are you at in your career? What part of the country are you in? Tell us a little about your marital status, etc.
Matthew:
I’m a second-year resident at Travis Air Force Base, Family Medicine. That’s in California. We’re about 60 minutes from Sacramento and 60 minutes from San Francisco, so right in the middle of both. I’m married. We actually just celebrated three years of marriage. My wife was a nurse while I was in medical school. Then she finished her MP degree. The exact same month, I finished my MD, and then we moved out to California.
Dr. Jim Dahle:
Okay. What state are you a resident of?
Matthew:
Technically, Virginia, even though I go once a year.
Dr. Jim Dahle:
Do Virginia residents pay state taxes on military income?
Matthew:
Unfortunately, I’m not in one of those great states.
Dr. Jim Dahle:
At least it’s a better rate than California.
Matthew:
It definitely is.
Dr. Jim Dahle:
Okay. Well, I rotated at Travis Air Force Base as an MS-4. I did some sort of a sub-I out there. The highlight of the trip is I went to climb Mount Shasta solo. I got up to, I don’t know, 13,000 feet or something. It was a total whiteout. I’m like, “What am I doing up here? I’m on some rocky ridge trying to get up there. I got to get out of here.”
Dr. Jim Dahle:
The only way I got off that mountain is I knew if I stayed between two ridges and walked downhill, I would eventually get to some trees and I’d be able to tell where I was. I walked off Mount Shasta with 50 feet of visibility. Never made the summit. I haven’t been back, but maybe someday I’ll get back to Mount Shasta.
That was my biggest recollection from that month at Travis Air Force Base. Thank you for your service. Thanks for being out there. I know those Air Force members appreciate you being there.
All right. Let’s talk about your milestone. It’s a net worth milestone. I think we’ve got another one. I think we’ve got two of these this month of residents who have built substantial net worth. Tell us what your net worth is.
Matthew:
Checking it out last night, it was at $170,000. Most of that’s just investments between my wife and I and then also some in cash.
Dr. Jim Dahle:
Very cool. Your wife, you mentioned, is an NP. Tell us what your combined income is as a military resident and an NP.
Matthew:
It’s actually pretty good. I think people expect military residents to make not that much money just based off civilian residents. This year, I’ll make $130,000. It looks like the president’s pushing hard for increasing our wages even more. Might be making $140,000 by the end of residency. My wife makes $100,000 a year.
Dr. Jim Dahle:
I won’t tell you what my pay was as an attending physician in the military. It was less than $140,000. Very cool. They have a way of getting it out of you by paying you a little bit less than you’re worth later. Usually, you have this commitment, I assume, because they paid for med school.
Matthew:
Exactly. I got a small stipend in med school. It was enough to get by, pay all the expenses, didn’t build a whole lot of wealth in med school, but definitely happy to graduate debt-free.
Dr. Jim Dahle:
Do you guys have any debt now at all?
Matthew:
Just a little bit. We used the USA Career Starter Loan, which is like 2.99%. We’re carrying that, but at the end of med school, we had very little in the bank. We paid for my wife’s school out-of-pocket, and she was working one shift a month. I was the primary breadwinner, making, I think, like $2,500 a month with my stipend. We had to take out a little bit of a loan in order to just pay for all the moving expenses to get from Virginia to California.
Dr. Jim Dahle:
You said you’re PGY-2?
Matthew:
Yes, sir.
Dr. Jim Dahle:
You’re only like 15 months out of school, both of you. Is that right?
Matthew:
Exactly.
Dr. Jim Dahle:
You’re making a couple hundred thousand dollars, which is awesome. But you’ve got $100,000 of it left. What did you live on the last year? How much did you guys spend?
Matthew:
I think we spent pretty well. At times, I felt like we were spending quite lavishly, but I would say we just automated it. Every month, money was going into our 401(k)s, going to our Roth IRAs, and then whatever was left over, we spent. We’re still spending $6,000 to $7,000 a month between rent and having fun, enjoying this great state that we live in.
Dr. Jim Dahle:
It is a beautiful place there at Travis Air Force Base. So many cool things to go. You can go down into the city. You can go out to Lake Tahoe and up to the ski resorts and up to Mount Shasta and out to the beach. There’s lots of fun stuff to do there. There’s no doubt about that.
I come across on this podcast as being anti-California. I actually love a lot of things about California. It’s just a challenging place to build wealth as a doc because of the cost of living and the particularly high tax rate that so many docs face there.
Tell us how you guys have done this. This is pretty awesome that you guys are already building wealth, but tell us how you got on the same page financially, why this is important to you, how you became financially literate, et cetera.
Matthew:
My grandfather grew up very poor in Kansas and he really wanted to make sure that my dad was going to know finances. So then my dad passed that on to me. My grandpa was nice enough when we graduated high school, he started a small brokerage account for each of the grandkids, put a thousand dollars in it, which is a very generous gift.
Then every Christmas, birthday, whatever, he would put a little contribution in, like $50 or so. Then when I started making money as a scribe, as a med student, got my signing bonus for the HPSP. I just started contributing monthly, so I probably put in like $12,000 to my Roth in med school too, just to try to make that a habit.
Dr. Jim Dahle:
I love this technique he used. Let me evangelize this for a minute for those of you who are a little older listening to this podcast. A lot of people have substantial difficulty overcoming the inertia to open an investing account. So, doing this for somebody, opening their account or taking them by the hand and opening it or having to be a custodial account and then converting it when they turn 21 or whatever, eliminates that barrier and really can get your family, friends, whatever, investing.
I think that’s awesome what your grandpa did. Not just the gift of the money, which is cool, but just the teaching that goes along with opening the account and showing you how to do it. I think that probably did have a lot to do with you. He’s literally changed his family tree. Your dad, now you, you’re going to teach this to your kids. Four generations he’s affected already. It’s pretty cool.
All right, keep going now that I’ve interrupted you. Tell us, eventually you met your wife. I assume she didn’t have grandpa teaching her how to invest.
Matthew:
No, she did not. And I remember we had a conversation one day, we were driving down the road and she was like, “Well, I don’t want to just never spend money and never travel.” And so then I had to take a step back and show her the math. And I ran through compound interest and all that. And once she saw the numbers, she was totally on board. She was very frugal before we even met too. She was making consistent payments through her undergrad loans and paying those off really fast, living below her means. And then once I just like kind of showed her what she was already doing and showed her the math, she was all on board and definitely loves it now just seeing how things are stacking up for us.
Dr. Jim Dahle:
You say showing the math, but I think there’s more to that process. It’s sharing your dream, sharing what you want later and saying, well, what does that take to have that later? I mean, it’s not just here’s how compound interest works. And look, we compounded 9%. We have a bazillion dollars in 20 years. It’s this is what we can do in five years, in 10 years, in 20 years, if we show a little discipline now and optimize things a little bit now. It’s pretty cool.
Matthew:
Yeah. So both of us, family, we don’t have any kids right now, but family’s everything. So once I showed her with the current rate we’re saving out, once we get to 45, 50, we can both work part time or not work at all. And once she saw that, she was definitely on board.
Dr. Jim Dahle:
That’s pretty awesome. This is classic millennial Gen Z, whatever you call it, I don’t know, where people are like, lifestyle actually matters more to me than there’s some 65 year old doc out there listening to this going, “Why would anybody want to work part time?” That’s so crazy. And of course, that’s gen Xers are stuck in the middle, looking at this on both sides going, “Well, you both are kind of right in your own ways.”
But it’s been interesting. It is true, though, that younger docs are far more interested in having more balance in their life, I think, than medicine traditionally did. How does paying attention to your finances, how do you expect that’s going to provide these options to you later in your career?
Matthew:
Just looking at things now, I don’t have any concern about finances. I know we’re on the right trajectory. And then I think once I’m 45 or 50, and we hit our financial independence number, I can keep serving patients and do what I love, but also have that time to hopefully be home and go to all my kids practices and spend time with my wife and future family.
Dr. Jim Dahle:
Have you decided yet if you’re planning to make a career out of military medicine? Are you planning on probably doing your time? Or do you even dare say I’m not sure I said when I was in your position. So feel free to not answer that if you don’t feel comfortable doing so.
Matthew:
No, it’s such a tough balance. I’ve run the numbers on both ends. I think probably would lose out a little bit financially long term doing the military, but it’s such an honor to serve every day. We have such a great population and I want to do sports medicine long term. The sports docs in the military get 30 to 45 minutes per appointment to sit down and really just handle everything for that patient where if I go work in an ortho practice and the civilian sector, I might make $200,000, $300,000 more per year, but I’ll be seeing patients in five, 10 minutes. So I don’t know if I know quite yet, but I see pros and cons to both.
Dr. Jim Dahle:
Very cool. Okay. For somebody out there thinking about doing HPSP to pay for med school, what advice would you give them?
Matthew:
Only do it if you really want to serve. I’ve heard you say this. I’ve heard dozens of other doctors say this, like you’ll hate it if you don’t want to be in the military. But I think if you have a true commitment towards serving, it’s the greatest opportunity of your life. I never would have pictured myself moving to California from Virginia. My whole family’s there. The HPSP just kind of enabled me to do that. I’ve gone to OTS and had some great education and leadership there. I got to fly a plane with a retired colonel and I get great training opportunities that I don’t think I ever would have had access to in the civilian world. And also the military just has the most incredible people that I’ve ever met.
Dr. Jim Dahle:
Very cool. Well, thank you for sharing that. Well, there’s somebody out there like you. That wants to kind of hit the ground running as a resident that wants to be building wealth already in their first year residency. What advice do you have for them?
Matthew:
Just got to automate everything. If all the money comes in to your savings account or checkings account, you’ll start spending it. But if you never see that money, it’s just going to get saved and you’ll spend the rest and live below your means. So, we automate everything. And then we also use an app called Copilot. I don’t know if you’re familiar with it, but it’s really helped us just to see where all our money’s going, because like most military folks, we played the credit card game and have too many credit cards.
And it was kind of hard to keep track of how much we were spending month to month. So that has allowed us to see how much we’re spending on every credit card and provides us like a nice line to see and make sure we’re not spending too much or going over our set budget.
Dr. Jim Dahle:
Well, congratulations to you on your success. And thank you so much for being willing to come on the podcast and share it with others.
Matthew:
Thanks so much for having me.
Dr. Jim Dahle:
All right, let’s wrap this up a little bit. Those of you in the military, remember that, yes, you get higher resident pay and you don’t have student loans. Those are the pluses. The minuses are that you’re going to get paid less.
So, in order to deal with that, you have to be a little more focused on wealth building during your training than a civilian resident does. The civilian residents focused on “Let’s make sure I got my disability insurance in place and my life insurance in place and that I’ve got my student loans on the right student loan plan. And I need a plan to hit the ground running when I become an attending.” That’s about it as a civilian resident.
As a military resident, it’s time to start building wealth. You have to act a little bit more like an attending. Yes, I know you’re not paid like an attending yet, but you need to be saving for retirement. You’re paid more. You don’t have student loan payments to be making. You really need to be getting up there saving 15, 20%-ish. You need to get going on this. You need compound interest to work for you.
The good news is, if you’re a military resident, you’re obviously in the military. You have access to the Thrift Savings Plan. Use the Roth version, not the traditional version. You’re this is just a no-brainer for military folks, almost everybody.
I’m sure there’s an exception out there, but there’s not very many of them. Because you’ll either get out of the military after four years or whatever, and you’re going to make a lot more money and you’ll be in a higher tax bracket. Or you’re going to stay in the military. You’re going to qualify for a pension, and that’s going to fill the lower tax brackets in retirement. You’re going to be glad either way that you did Roth now.
You don’t have to play any of these games with traditional IRAs and traditional 401(k) contributions as a resident that some residents are playing in order to manipulate the student loan game to keep their income down so their student loan payments are low so they can get more public service loan forgiveness. That’s not you. You don’t have loans.
So Roth, Roth, Roth, Roth, Roth. And start stuffing money in there and start building wealth like these guys. Make sure you got a plan for disability insurance and that sort of stuff. But mostly it’s just time to get going investing. If you are a military resident, you need to be investing. Use your Roth IRA, use your Roth TSB, get any match they’re going to give you. Of course, that’s a priority.
Not getting that is leaving money on the table. It’s part of your salary on the table. Don’t do that. And of course, if your spouse is working, you can max out their retirement accounts as well. But it’s time to act a little more like an attending than you would, I think, if you were a civilian resident or fellow where you can kind of delay this a little bit because you’ve got a higher income coming later. Your income is not going to be that high as an attending. So you got to get going, let compound interest work a little bit more for you.
FINANCIAL BOOT CAMP: GLIDE PATH
Dr. Jim Dahle:
A guide path is simply the way in which your asset allocation or mix of different investment types changes over time. Classically, people take less risk with their investments as they get older. And so, their asset allocation becomes more conservative, less aggressive as they move toward retirement and then into and through retirement and approach their ending years.
Classically, people have started out with 80% or 90% or 100% stocks in their 20s. And then as they move toward retirement, they’re down to 60% stocks or something like that. And they continue to reduce that risk they’re taking throughout their lives. That is what most people mean when they say an investment-wide path. And you can change that in intervals. You can change it every five years. You can change it every year and just gradually make it less aggressive as you go.
There is some pushback to this, of course. There are some studies suggesting that, yes, you do need to increase the amount of risk you’re taking right around the time you retire, but then can actually take more risk as you go throughout retirement. That might help protect your portfolio growth from high inflation. And so, it deals with the sequence of returns risk where you’re trying to avoid losing a bunch of money just before you retire or just after you retire.
Sequence of returns risk, of course, is that risk that you run out of money in retirement despite having adequate average investment returns to support your withdrawals because the poor returns came first. And withdrawing from a portfolio that’s dropping in value is a pretty good way to decimate it quickly. That’s sequence of returns risk. And so taking less risk in your portfolio around the time of retirement is a good way to reduce that risk.
So, that’s the main reason why investors change their asset allocation over time. They have been gradually converting their earned income, their potential income into actual assets, physical assets that are going to live on during retirement. So it’s a gradual process as you put in your time and effort and sweat and tears throughout your career because you’re slowly losing time and you’re gaining money. And because you have less to put in there as time goes on the idea is you take less risk as you go on.
And so, there are funds called funds of funds or target retirement funds or life cycle funds that try to do this for investors. They don’t have to do this manually themselves. So if you go invest in a Vanguard target retirement 2060 fund, they design it for somebody that’s going to stop working in 2060. When you first start investing in that in 2020 or 2025 or 2030, it’s going to be pretty aggressive. It’s going to be like 90% stocks.
Then as you get closer and closer to retirement, it’ll be 80% stocks and 75% stocks and 70% and 65%. Until the time you retire maybe it’s 60% stocks or 55% stocks. And then a few years after you retire, maybe it’s even less than that. That’s the concept of a target retirement fund. Not only does it rebalance itself between the various different asset classes, but it comes more conservative over time. So, that can be a great one-stop solution, at least for those that invest only in retirement accounts like Roth IRAs and 401(k)s.
There’s some reasons why maybe it’s not a great asset to use in a taxable account, but it’s a great one-stop shop, especially for a resident or somebody just starting to save for retirement with all their money in a Roth IRA or something like that.
Common mistakes people make when creating or following a glide path is maybe making it too steep to where they get too conservative too early or not making it steep enough. There are some people that haven’t changed their mix of investments from the time they were 95% stock at 25 and here they are at 60 and they’re still 95% stock. Well, maybe that’s a little too much risk for you to be taking. And maybe you should have made that glide path a little bit steeper.
So, those are the main issues, is just not making it steep enough and making it too steep. And what’s right depends on you. Even the various financial companies that build these target retirement funds don’t necessarily agree on exactly how steep that glide path ought to be. They might differ by 10% of a stock to bond ratio, might be different from one company to another. So, it’s best if you lift up the hood and look underneath and see how does the glide path really change as the years go by and is that okay with me?
And you’re not stuck with it as long as you didn’t buy it in a taxable account. If you’re like, I’d rather be a little more aggressive, in five years you can change from the target retirement 2060 fund to the 2070 fund. And now your glide path won’t become more conservative for a period of 10 years longer than it otherwise would have.
Really, when you’re setting your asset allocation, you want to pay attention to your need, ability and desire to take risk. So, hopefully as time goes on, you acquire more assets, your need to take risk goes down. And maybe you’re very wealthy and your ability to take risk has actually gone up. Then you’ve got to figure out how those two things balance each other out.
But really, we’re just talking about setting your asset allocation and how it’s going to change over time. So I suggest when you put together a written investing plan, that you actually decide in advance, how is your asset allocation going to change over time? You might decide, “Well, I’m going to do it all at once. When I turn 55, I’m planning to retire at 60, I’m going to go from 80-20 to 60-40 at age 55, five years in advance. That’s the only change I’m going to make. I’m going to stick with that throughout retirement.”
You can make it very simple, or you can do something like the target retirement funds are doing and become 1% less aggressive every year. It’s up to you how you design your glide path, but give some thought to how your asset allocation is going to change as you move toward and throughout retirement.
SPONSOR
Dr. Jim Dahle:
Mortar Group is a premier real estate investment firm focused on multifamily properties in both ground-up and value-add projects in the competitive markets of New York City since the early 2000s.
With over $300 million in asset center management and over 30 investments since inception, their fully integrated firm model allows Mortar to maximize efficiency and value across their investments in these niche markets.
Mortar leverages over two decades of experience in architecture, development, and asset management in their projects to build value and minimize risk for investors. Invest in tax-efficient, high-return, risk-adjusted strategies with Mortar Group at whitecoatinvestor.com/mortar.
Okay. I hope you enjoyed that interview. It’s always fun to talk with you guys. You’re all over your careers. People are millionaires. People are paying off mortgages. People are paying off student loans. People are just getting going. People are decamillionaires.
I don’t care where you’re at. The point isn’t to compare yourself to other on the interview. The point is to take the lessons they learned and apply them towards your goals. This is a single-player game. You against your goals. That’s all you have to beat. You need enough for you, not enough for them, not more than them. You don’t have to beat the S&P 500. You have to have adequate returns to meet your goals. Stay focused on them. Make sure they’re aligned with your values. Make them as specific as you can. Make them smart goals. Specific, measurable, achievable, relevant, time-limited goals. Get going on them.
Keep your head up and shoulders back. You’ve got this. The whole community is here to help you. Don’t forget about that FEW event coming up on the 22nd. We’ll see you next time on the Milestones to Millionaire podcast.
DISCLAIMER
The White Coat Investor podcast is for your entertainment and information only. It should not be considered financial, legal, tax, or investment advice. Investing involves risk, including the possible loss of principal. You should consult the appropriate professional for specific advice relating to your situation.
Financial Boot Camp Podcast
INTRODUCTION
This is the White Coat Investor Podcast: Financial Boot Camp, your fast track to financial success.
Cole Anderson:
Hey, everyone! My name is Cole with White Coat Planning, and today Jim has asked me to get on here and teach you a little bit about donating appreciated securities. There’s an age-old saying that friends don’t let friends donate cash to charity. Now, don’t get me wrong. I love when people give to causes that they care about. Donating to charitable causes and organizations that we truly care about is one of the most important and powerful ways that we can spend our money. So when I say something as provocative as, “Friends don’t let friends give cash to charity,” I mean that literally. I mean cash. What I mean by that is that there is a smarter and better way to do it. I’m not discounting giving to charity, but we want to do it a little bit smarter than just handing over cash.
Before I get into it, I want to say that the reason to give to a charitable cause that you truly care about should be your desire to support that cause, that charity, that organization, or a religious tie. That should be the start and the finish of it. Any kind of tax advantage or deduction that you may get as a result of a charitable gift should not be the main goal. But if that’s something that’s out there, we want to be able to take advantage of it when it’s present.
My favorite way, and perhaps the best way, to donate money to charity is by donating appreciated securities like stocks, mutual funds, crypto, real estate, and all other types of investments too. When these securities are donated to a charity, the donor, meaning you, qualifies for the full charitable deduction as long as the investment that you’re donating has been held for at least one full year. So, 366 days plus, you get that deduction for the full value of the donated investment at the time that the gift is made. This also assumes that the donor is itemizing their deductions for taxes, so that’s another important note to consider. We’ll talk about that a little bit more later.
Additionally, the donor does not have to pay any capital gains taxes on the investment, and of course, neither does the charity. The charity gets the full value of the investment, and the IRS gets nothing. It’s a pretty good deal, if you ask me.
Now, let me give you an example of how this would work in real life. Let’s say that you’re a high-income doc, comfortably in the top federal tax bracket of 37%. For this example, we’re going to avoid state taxes because it’s just not very simple. So, let’s say that you want to donate $10,000 to your local animal shelter. Realistically, you could just write a check, collect the charitable deduction of $10,000, and move on with your day. That $10,000 gift would save you approximately $3,700 in taxes due with the charitable deduction, and that’s not bad at all.
Now, a note for the more detailed financial nerds out there: in reality, if you’re in the top tax bracket, there’s the 2/37 rule that would actually keep your deduction a little bit closer to $3,500, but we’re not going to talk about that today.
Now, I believe that there’s a better way to donate this money to this animal shelter. Instead of donating cash, let’s say you donate $10,000 in shares of VTI that you’ve been holding for several years in your taxable brokerage account. Now, let’s say those shares are at a 50% capital gain, meaning that your cost basis on that $10,000 is $5,000. In this scenario, if you donate the shares of VTI to the animal shelter, the shelter will then sell the shares and use the $10,000 in proceeds that they get to fund their operations. As a donor, you lock in that same $10,000 charitable deduction, saving you that $3,700 in taxes. But you also save on the capital gains that you would have paid on the $5,000 in appreciation that the shares of VTI had. If we assume a top capital gains rate of 20%, that’s another $1,000 that you’re not going to give to Uncle Sam, increasing your tax deduction by a little over 20% for the exact same gift amount.
Now, prudent WCIers will note that the best practice is to use your cash flow that was originally going to go to the animal shelter in this scenario to buy $10,000 in new VTI shares after you make that gift. So now you’ve accomplished your philanthropic goal with the $10,000 in VTI that you’ve gifted to the animal shelter. You’ve shaved off about $4,700 from your tax bill, and you remain fully invested in the stock market with a step up in basis.
Typically, most 501(c)(3)s can handle the donation of securities directly. So, if you’re worried about that, you really shouldn’t be. If it does become an issue, though, you can give appreciated securities to things like a donor-advised fund, which Jim has done several hour-long podcasts on, or something like a charitable checkbook. Typically, these types of alternatives alleviate any hiccups that may come up with smaller or local 501(c)(3)s or even your local church.
For clients that tithe, donating appreciated securities can meaningfully change your tax bill and your financial life. I won’t pretend to be an expert on religious tithing, but in my experience, I’d say that the typical amount is about 10% of your income. So if you’re a doc that tithes 10% of your income annually and you switch to donating appreciated securities, you can meaningfully increase your tax deductions without changing up your cash flow whatsoever. The money you’re saving on taxes can then be reapplied to other areas of your financial plan, like spending, saving, or, if you’re so inclined, increasing your giving.
Now, a couple of important notes here before I sign off. First, your charitable deduction is capped at 30% of your adjusted gross income with a five-year carryover period. In other words, or more simplistic terms, if your adjusted gross income is $100,000, you can donate up to $30,000 per year of appreciated stock and still receive the full charitable tax deduction. If you donate more than $30,000 with that same level of AGI, you can roll over or carry forward that additional deduction for up to five years.
For example, if you donate $50,000 in a given year when you make $100,000, $30,000 would be deducted in year one, and then $20,000 would be carried over and deducted from your income in year two, as long as that $20,000 is still less than 30% of your AGI in the next year.
Like I mentioned before, securities donated to charity must be held for more than one year, so at least 366 days in your ownership, in order to claim the full deduction for the value of your investment. If you hold them for less than that time, you can still give them to charity, but you’re going to be subject to just deducting your cost basis. It’s just less than ideal.
Another thing that I want to reiterate is that this only works if you itemize your deductions on Schedule A. With the One Big Beautiful Bill Act that was passed last year, a lot more people will be itemizing in the future. So if you think about your SALT deduction and if you have a mortgage on your big doctor house and are paying a decent amount of mortgage interest, you should probably be itemizing now, even if you do not donate to charity in a given year.
This last note is very important. For all non-cash charitable contributions over $500, so most people in this scenario donating appreciated securities, you must file IRS Form 8283 with your tax return. Okay, I’ll reiterate: file IRS Form 8283 with your tax return. So if you’re going to donate appreciated securities to a charitable organization that you care about, or to your church or whatever, please make sure that your CPA or your tax preparer, even if that’s you, gets this form ready. Thanks.
DISCLAIMER
The White Coat Investor Podcast is for your entertainment and information only and should not be considered financial, legal, tax, or investment advice. Investing involves risk, including the possible loss of principal. You should consult the appropriate professional for specific advice relating to your situation.
Did you find this article helpful? Share it!